Knowing how to invest during a recession comes down to four things: a cash reserve, no high-interest debt, a diversified low-cost portfolio, and a written plan you do not rewrite in a panic. A recession pushes prices down, which lowers what you pay for every future share you buy, so the useful response is usually to keep buying on schedule rather than to sell. Here is the order of operations, in plain US terms.
This is the version I wish someone had handed me before my first real drawdown. It takes maybe two hours of work spread over a week, and most of it is arithmetic rather than nerve.
Table of Contents
- What You Need
- Step-by-Step
- Step 1: Assess your financial foundation
- Step 2: How to invest during a recession with a diversified portfolio
- Step 3: Match investments to your time horizon
- Step 4: Invest according to a written plan
- Step 5: Rebalance and stay invested
- Common Mistakes
- Frequently Asked Questions
- What are good investments for a recession?
- Is investing during a recession a good idea?
- What should I not do during a recession?
- How much cash should I have during a recession?
- Are bonds better than stocks during a recession?
- Does gold protect against a recession?
- Conclusion
What You Need
First, the vocabulary, because most bad decisions start with a category error. A recession is a broad, significant decline in economic activity, and the National Bureau of Economic Research dates them by looking at real output, employment, income and industrial production, most often after two consecutive quarters of falling real GDP. A bear market is a 20% decline in market prices, which can happen without a recession, and a market correction is a drop of roughly 10%. Prices falling is not the definition of recession, and confusing the two is what leads people to panic-sell a healthy plan.
If you want to know whether one is actually underway rather than merely rumoured, watch three published series: the NBER’s own dating announcements, the unemployment rate from the Bureau of Labor Statistics, and the manufacturing and services surveys that track business activity. Investors also watch the yield curve for an inversion, because it has preceded several recessions, though it raises false alarms too. None of these are perfect timers, which is exactly why your plan cannot depend on calling one.
With that settled, here is what you need on the desk before you change a single holding.
- An emergency fund. Three to six months of essential expenses in a liquid, FDIC- or NCUA-insured account. The popular 3-6-9 version scales it: three months if you have two stable incomes, six if one income carries the household or yours is cyclical, nine if you are self-employed with no employer insurance.
- A debt list with current balances and rates. Credit cards and personal lines usually sit at the top. You cannot weigh paying them off against investing without seeing both numbers side by side.
- One page describing your goals. What the money is for, and the earliest date you might need it.
- Your time horizon and honest risk tolerance. A ten-year horizon tolerates drawdowns a two-year horizon does not, and pretending otherwise is how people end up selling at the bottom.
- A current holdings list. Account type, balance, and roughly what percentage each holding is of your total.
- A written statement of your plan. Allocations, contribution amount, rebalance trigger, and the date you will review it. Writing it now is what keeps a later decision honest.
Keep the cash fund and the brokerage account separate, ideally at different institutions. The entire point of a cash buffer is that it stays put while the rest of the portfolio moves.
Step-by-Step
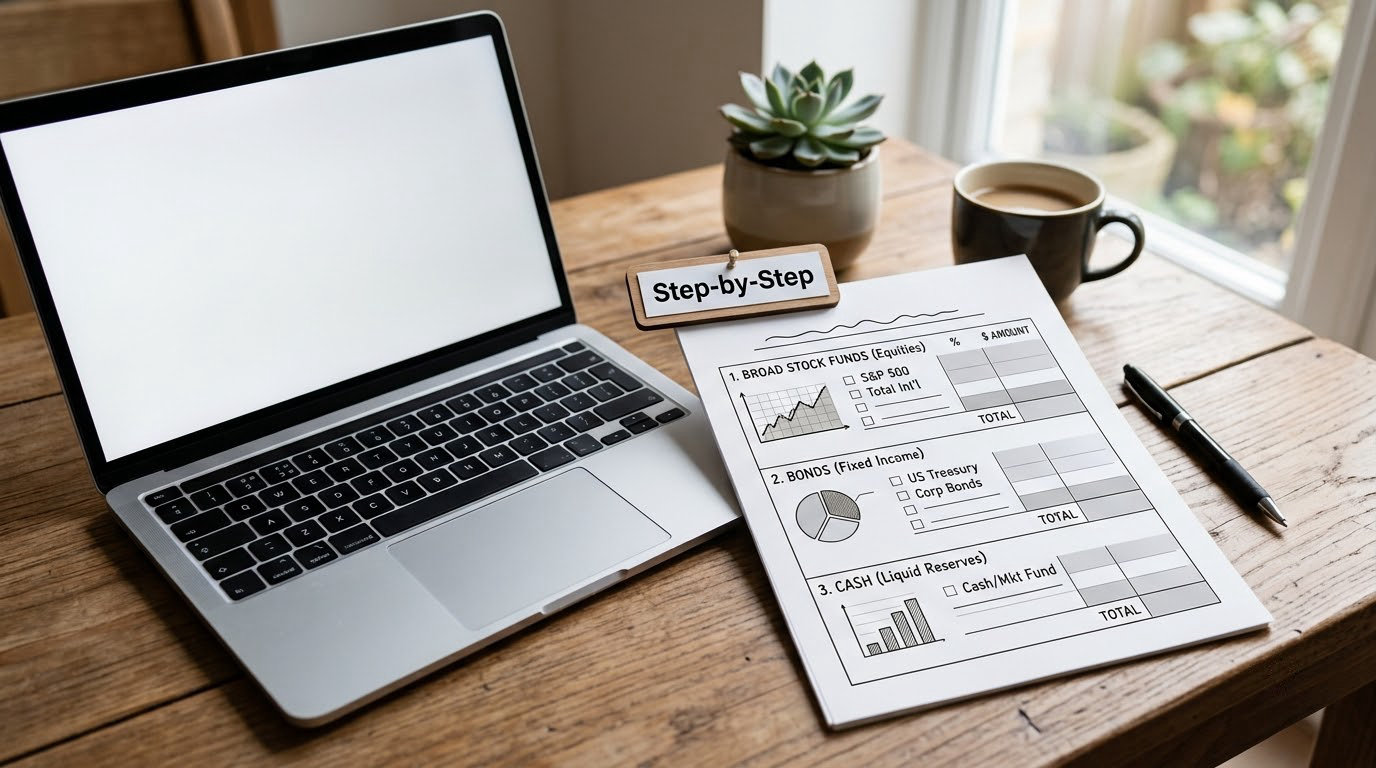
Five steps, in this order. Skipping ahead to step two while carrying credit card debt and a six-week cash buffer is the single most common expensive mistake in a downturn.
Step 1: Assess your financial foundation
Add up what you would need to cover if your income stopped entirely. Subtract your current cash reserve. That gap is your real risk during a recession, and no allocation fixes it.
Next, compare each high-interest balance with what your investments are realistically likely to return. A card balance in the high teens is a guaranteed negative return. An index fund is an uncertain positive one, and in most years the guaranteed number beats the uncertain one, which is why clearing that debt usually outranks new purchases.
Confirm that no bill due in the next two years is being paid from a position that can fall 30%. If it is, move that amount to cash or a short-dated Treasury before you go any further. You will know this step worked when you can state, in one sentence, how many months of expenses you could cover without touching the market.
Step 2: How to invest during a recession with a diversified portfolio
Diversification is the part that does the actual work in a downturn, and it means holding assets that do not all fall together. A broad equity index fund spread across US large, mid and small companies behaves nothing like a portfolio of five technology names, even though both are labelled stocks. Add international equity, investment-grade bonds, and short-term Treasuries, and you have most of the shape of a balanced portfolio.
Favour low-cost vehicles, since an expense ratio is a certain cost and the return is not. Broad index funds and plain-vanilla ETFs are the usual choice. Check the expense ratio before you buy, and be suspicious of anything charging more where the underlying holdings are the same index everyone else owns.
Look at your holdings and ask one question: if the single worst sector falls another 40%, does my portfolio survive it? Sectors are the most common concentration, then single employer stock, then a favourite company. Trimming the largest position down toward a target weight is a defensible action during a downturn; selling because of an article you read is not.
Step 3: Match investments to your time horizon
The same dollar needs different treatment depending on when you need it. Money for a house in eighteen months and money for retirement in twenty-five years should not sit in the same account, no matter how convenient that would be.
| Time horizon | Suitable holding | Why |
|---|---|---|
| Under 2 years | High-yield savings, money market, Treasury bills maturing near the date | A 30% equity drop right before you buy is a real loss, not a discount |
| 2 to 5 years | Mostly short Treasuries and high-quality bonds with a small equity sleeve | Less time to recover, so the cost of volatility rises |
| 5 to 10 years | Balanced mix of bonds and equity funds | Some cushion, enough horizon to absorb a cycle |
| 10 years and beyond | Majority in diversified equity funds, rebalanced annually | Time to ride out a drawdown and recover |
These are illustrative groupings, not recommendations, and your own horizon may not land neatly in one row. Retired or near-retired investors face a specific version of this problem: starting withdrawals while balances are low is the worst possible ordering, so a larger cash and short-duration position matters more for them than for a twenty-five-year-old.
Step 4: Invest according to a written plan
Write the plan down before you need it. Four components: a target allocation expressed in percentages, a contribution amount you can keep paying through a pay cut, a rebalance rule such as adjusting once a year or when any weight drifts five percentage points, and a review date on the calendar.
Contributions are where dollar-cost averaging does its quiet work. Putting the same amount in every month means you buy more shares in cheap months and fewer in expensive ones, and you never have to make the call. Many people who have done it this way for a decade would not trade the discomfort for anything.
One named rule worth borrowing, often attributed to Warren Buffett, is to keep ten percent of your money in short-term government securities and ninety percent in equities. It is a sanity check against a portfolio so conservative it cannot beat inflation, or so aggressive it forces you out at the worst moment. Treat it as a guardrail, not a command.
Step 5: Rebalance and stay invested
Rebalancing is the least exciting and most reliable habit in the whole plan. Selling some of what has risen and buying some of what has fallen mechanically pulls you back toward your targets without asking you to predict anything.
Do it on the schedule you wrote down, not on a day the market moved. Most quarters you will do nothing at all, which is the correct outcome. When you rebalance in a downturn you are buying more of the beaten-down asset at the same contribution, which is a genuine benefit of having cash queued for exactly that moment.
Finally, separate two very different signals. A 15% drop in a week is volatility, and volatility is normal. A change in your job, your health, your family, or your goal is a reason to revisit the plan, and only that. You will know this step worked when a bad month on the statement leaves your allocation unchanged and your review date untouched.
Common Mistakes
Most recession losses are behavioural, not analytical. The same set of errors shows up every cycle, and each has a straightforward fix.
Selling everything and sitting in cash. Investors on investing forums consistently describe the same pattern: they sold at the point of maximum pessimism and watched the recovery pass them by. The fix is a written rule requiring a cool-off period, ideally thirty days, before any sale of a long-term holding.
Trying to time the bottom. Nobody has reliably called the low point of a market in advance, and the people who claim otherwise are usually being paid to promote something. If the idea of being wrong by half sounds acceptable, stay invested; if it does not, your stock allocation was too high to begin with.
Investing money earmarked for emergencies. A fund that was meant to cover a car repair should not be in equities when the repair comes due. Keep the buffer in cash and let the long-term money stay long-term.
Chasing whatever is moving. Panic-era narratives arrive after prices have already tripled, not before. Turnover during a drawdown is high in both directions, and fees and taxes turn trading into a permanent drag.
Ignoring fees, taxes and the wash sale rule. Expense ratios compound against you every single year, and harvesting losses can be spoiled if you repurchase a substantially identical holding within thirty days before or after the sale. Track the trade date, not the settlement date.
Changing the plan without a reason. If the reason is a headline, there is no reason. If the reason is that your goal, horizon, or income actually changed, rewrite the plan on paper and keep the review date.
Two further habits that cost nothing. Put a real employer match before you put money anywhere else, because a match is an immediate return on the contribution. And keep paying retirement contributions through a downturn when your income allows, since contributions at depressed prices buy more shares of the same thing.
Frequently Asked Questions
What are good investments for a recession?
Broad, low-cost index funds spread across US and international equities, plus investment-grade bonds and short-term Treasuries, are the standard answer for most people. Within that, tilting part of the equity sleeve toward sectors with steady demand, such as healthcare, consumer staples and utilities, is a reasonable choice. Individual stocks and leveraged products carry far more risk than a downturn rewards. Illustrations only, not recommendations.
Is investing during a recession a good idea?
For someone with a cash buffer, no high-interest debt, and a goal ten or more years out, yes. Falling prices mean each new contribution buys more shares of the same holdings, and a broad index has recovered from every past US recession eventually. For anyone funding near-term bills from investments, or carrying credit card debt, the priority order reverses entirely. First secure the cash and the debts.
What should I not do during a recession?
The recurring errors are panic selling everything, attempting to call the exact bottom, investing money reserved for emergencies, chasing whatever is rallying, and rewriting a plan because of a headline. Also worth avoiding: concentrated single-stock and single-sector positions, leveraged products and options, and market-timing cash moves. Every one of these has a clear fix, which is to follow the written plan you made when your judgement was calm.
How much cash should I have during a recession?
Three to six months of essential expenses is the usual guidance, and the right end depends on how stable your income is. Two steady salaries point to the lower end; one income, a cyclical job, or self-employment points to six months or more. Keep that money in an FDIC- or NCUA-insured high-yield savings account or short Treasuries, separate from your brokerage account, so it is there when you need it.
Are bonds better than stocks during a recession?
Bonds often fall less than equities during a downturn and can rise as the Federal Reserve cuts rates, which is why they carry ballast in a balanced portfolio. But bonds are not risk-free: high-yield bonds are closer to equities, and a long-duration portfolio can drop when inflation stays high. Treat bonds as the stabilising share of a portfolio, and keep genuinely near-term money in cash and bills rather than in anything long-dated.
Does gold protect against a recession?
Gold has a long history as a store of value when confidence in other assets drops, and some investors hold a small allocation for that reason. The honest counter-argument matters: gold fell sharply in the weeks after the March 2020 crash as investors scrambled for cash, and it can decline for long stretches without helping. Treat it as a diversifier in small size, not as the answer to the question of how to invest during a recession.
Conclusion
Start with the unglamorous part. Count what you would need to cover if your income stopped, hold that in an insured savings account, and clear any high-interest balance, because those two moves remove the only genuinely dangerous part of a downturn: being forced to sell.
Then write the plan down. Name the goal, the date you might need the money, and the share of the portfolio that can fall a third without changing your life. Buy broad, low-cost holdings on a schedule you can keep, hold a real employer match, and rebalance once a year without drama.
A recession is a discount on the future, not an instruction to leave the market. As of 2026, the work that pays is preparation you do before the headlines arrive.
This article is educational information about personal finance, not individual investment advice. Rules, tax treatment and rates vary by circumstance and change over time. Consider a fee-only fiduciary adviser or a tax professional for advice on your specific situation. Past performance does not predict future results, and nothing here is a guarantee of return.