The fastest way to know how to choose a financial advisor in the US is to confirm they operate as a fiduciary, then compare their fees line by line against the services you actually need. Check their regulatory record with FINRA BrokerCheck and the SEC’s Form ADV, and interview at least three candidates using the same questions before anyone handles your money.
That is the short version. The longer answer is that most people hire an advisor on a first impression, and first impressions are the part that gets sold hardest. A friendly lunch, a polished planning deck, a nice office. The vetting is what protects you.
Here is the checklist I would use, and the reasoning behind each item:
- Fiduciary status. RIAs are held to a fiduciary standard of care; a broker-dealer is not. Know which one you are sitting across from.
- Fee structure. Understand whether you are paying an asset-based fee, a flat fee, an hourly fee, or nothing while someone earns a commission behind the scenes.
- Credentials and niche. A certification matters less than whether they regularly work with people whose situation resembles yours.
- Regulatory record. BrokerCheck and Form ADV take about ten minutes to read and turn up more than a glossy brochure ever will.
One note before we go further: mapness.net does not sell financial products, sell leads to advisors, or take a referral fee. Nothing below is personal financial advice. Fee levels and rules differ by state and change over time, so treat every number here as a starting point to verify with the advisor in front of you.
Table of Contents
- What You Need
- How to choose a financial advisor: questions to ask
- Step-by-Step: How to Choose a Financial Advisor
- Step 1: Define your goals and the help you actually need
- Step 2: Decide which credentials and legal status you require
- Step 3: Compare fees, services, and account costs
- Step 4: Check investment approach, conflicts, and customization
- Step 5: Verify experience, discipline history, and references
- Step 6: Interview several advisors with the same questions
- Step 7: Check the agreement before hiring
- Common Mistakes
- Frequently Asked Questions
- How do I know if a financial advisor is a fiduciary?
- How much does a financial advisor cost?
- What is a typical fee for a fee-only fiduciary?
- Are robo-advisors better than human financial advisors?
- How do I check a financial advisor’s disciplinary record?
- How do I switch financial advisors without losing money?
- Conclusion
What You Need
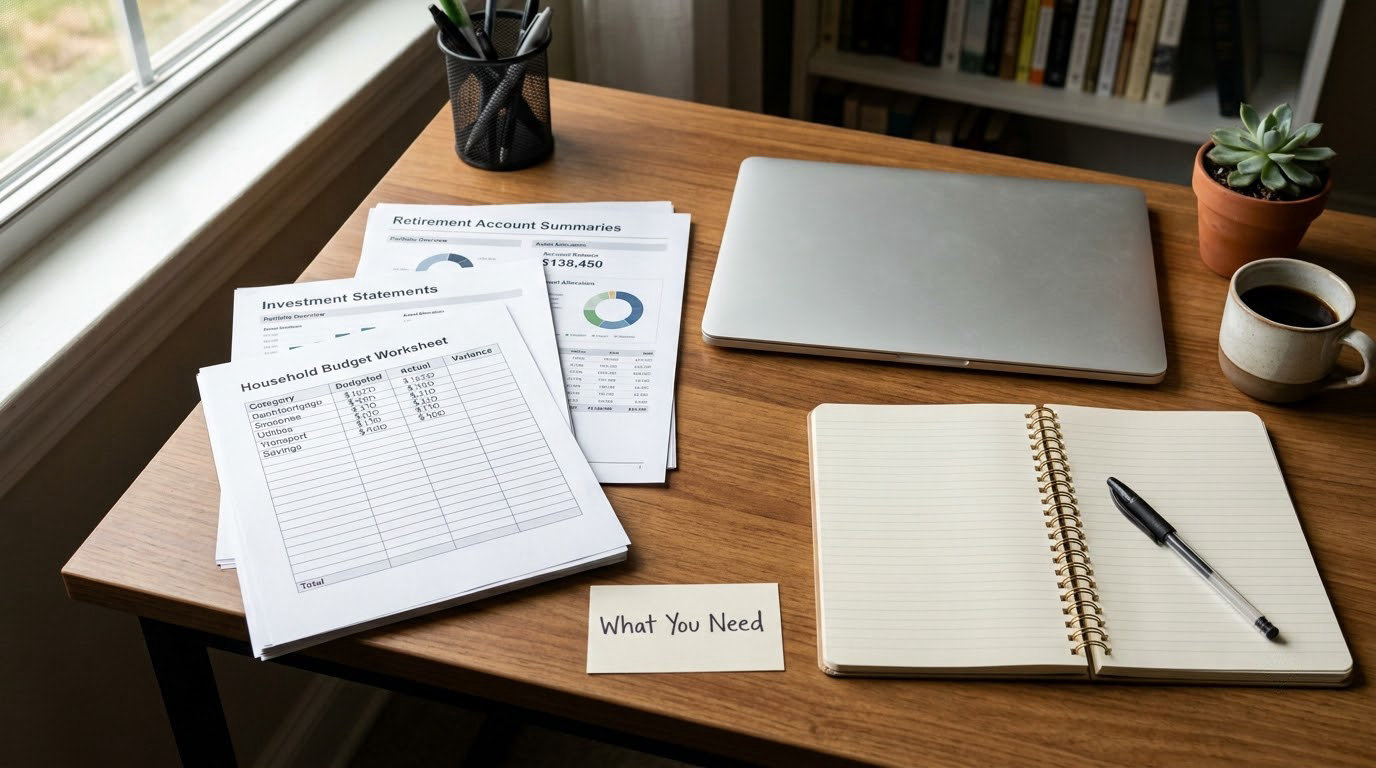
Gather your own numbers before you gather advisors. An advisor cannot quote you a sensible fee or build a sensible plan if they do not know what you own, what you owe, or what you are trying to do.
What to have on the desk before the first call:
- Goal statement, written. Retirement date, target annual spending, and the two or three decisions coming up in the next five years. One page is plenty.
- Every account statement you can find. Retirement plans from old employers, individual brokerage accounts, bank balances, and any employer stock or options.
- The tax picture. Last two years of federal returns, plus a rough sense of whether you have a year coming up with unusual income or deductions.
- Liabilities. Mortgage balance and rate, student loans, credit cards, and any business debt.
- Beneficiary and estate documents. Wills, trusts, and who has power of attorney on file at each institution.
- Blank comparison sheet. Create this before the interviews so every candidate gets the same columns filled in.
Old 401(k) balances deserve special attention. Frequently changing jobs leaves a trail of dormant accounts nobody is watching, and finding them is one of the more useful things a good advisor does for you.
How to choose a financial advisor: questions to ask
Ask these seven questions first, before any discussion of returns or performance. Each one filters the field fast, and each one changes who the right candidate is for you.
- Are you a fiduciary, and in what capacity? Determines the legal standard they owe you.
- How do you get paid, in total? If the answer avoids the words, keep asking.
- What services do you provide beyond picking investments? Tells you whether you are paying for planning or for asset allocation.
- Who is your custodian, and who has access to my accounts? Answers the security and privacy question in one breath.
- What does a typical year look like for a client like me? Reveals real service level instead of promised service level.
- What have you done recently with someone in a similar situation? Experience shows up in specifics, not adjectives.
- Who handles my account if you leave the firm? The honest answer is usually a named colleague or a transition plan.
Step-by-Step: How to Choose a Financial Advisor
Seven steps, in this order. Skipping ahead to the interview is the most common mistake, because without a written goal you cannot tell whether an answer was any good.
Step 1: Define your goals and the help you actually need
Start by separating planning from management, because they are two different jobs with two different price tags. A financial plan is usually a defined deliverable: a written document covering cash flow, retirement projections, insurance gaps, and an action list. Ongoing management means someone holds your portfolio and adjusts it over time.
You may need one, the other, or neither. Someone with a simple employer plan, no debt and steady savings can often run three broad index funds and be better off than paying an asset-based fee every year. That is not a failure of the advisor industry; it is arithmetic. A fee of roughly 1 percent of assets per year is a permanent, compounding subtraction from your balance.
Hire ongoing help when the work is genuinely hard to do alone: a business you own, equity compensation that vests over years, several old employer plans, a divorce, an estate to settle, or a retirement date inside ten years where the income math is unforgiving. Write your answer down. You will want it in front of you in Step 6.
Step 2: Decide which credentials and legal status you require
The legal category matters more than the business-card title. Registered investment advisers are registered with the SEC or a state regulator, owe a fiduciary duty, and are typically fee-based. Broker-dealers are registered with FINRA, are held to a suitability standard rather than a fiduciary one, and are usually compensated through commissions and spreads, which can include trailing commissions paid out of the funds they sell.
Robo-advisors automate allocation and rebalancing, charge roughly 0.25 to 0.50 percent, and suit straightforward portfolios. Financial planners focus on the plan itself rather than ongoing portfolio management, and often work hourly or for a flat fee. Insurance and annuity brokers sell products that pay them a commission, sometimes for many years, which is the single largest conflict in the industry.
Credentials tell you less than people assume. A CFP from the CFP Board of Standards signals broad planning training and requires continuing education. A CFA from the CFA Institute is an investment-analysis designation. A CPA is a tax credential. A ChFC and a CLU focus on insurance and estate topics, and a CIMA on investment management. None of them certifies judgment, and none of them tells you how many clients the person carries.
Two practical checks matter more. Ask whether they hold the certification in the seat, rather than at some firm down the hall. And ask what they are licensed to sell, because the license list maps directly onto the pressure you will feel later.
Step 3: Compare fees, services, and account costs
Cost is the one variable where a small number becomes enormous over decades. A 1 percent annual asset-based fee on a 500,000 dollar portfolio is 5,000 dollars in year one, and it repeats every year whether the market cooperates or not. The comparison below is worth printing.
| Fee model | Typical US range | Works well when | Watch for |
|---|---|---|---|
| Asset-based (AUM) | Roughly 0.5 to 1.25 percent a year, often tiered | Your balance is large and growing | The fee is charged on the whole balance, so small portfolios get hit hardest in percentage terms |
| Flat fee | Often 2,000 to 7,000 dollars for a written plan | You want one defined deliverable | Confirm whether revisions and follow-up are included |
| Hourly | Often 200 to 400 dollars an hour | You have a narrow, specific question | Scope creep, so agree a written estimate before the first call |
| Subscription | Monthly or annual membership, often with a tier cap | You want planning access without giving someone custody | Whether advice is unlimited or capped at a set number of hours |
| Commission-based | Nothing on the surface, money inside the products | Almost never, as your sole arrangement | Sales commissions, trailing fees, and the surrender charges that follow annuity recommendations |
| Hybrid | A small retainer plus asset-based fees | Complex situations with real planning work | Read both halves of the schedule and check for overlap |
| Robo-advisor | Roughly 0.25 to 0.50 percent a year | Simple portfolios needing disciplined rebalancing | Little help with taxes, equity comp, or estate work |
Then look past the advisory fee, because it is rarely the full bill. Ask for the all-in number: advisory fee, fund expense ratios, trading costs, and any administrative or plan fees. Industry analyses put the average all-in cost of advised portfolios at roughly 1.65 percent a year, so an advertised 0.50 percent fee can still arrive at well over one percent once funds are counted. A wrap fee bundles the advisory and fund costs into one line, which is convenient but hides what you are actually paying for.
Account minimums deserve the same attention. Plenty of quality practices set a floor somewhere in the 250,000 to 500,000 dollar range for ongoing management, which is why so many readers end up asking about hourly or flat-fee alternatives. That is not a rejection; it is the market telling you the economics do not work at your size.
Step 4: Check investment approach, conflicts, and customization
Every recommendation comes with someone else’s revenue attached. Find out where it comes from.
Ask directly whether they or their firm receive commissions, referral fees, or compensation for recommending particular products. Ask what happens when the highest-paying product is not the best fit for you, and listen to the answer rather than to how it is phrased. Firms often house their own funds or annuities, and every dollar you put in one of those can carry a trailing commission nobody will mention unless you ask.
On customization, the tell is whether the portfolio is built from your numbers. A good first meeting produces a written asset allocation tied to your time horizon and your honest capacity for a bad market year, not a house model applied to everyone. A philosophy of low-cost index investing is a legitimate answer. So is active management, provided they can explain where the edge is supposed to come from and what happens when it does not.
Step 5: Verify experience, discipline history, and references
Verification is the step people skip, and it is the cheapest insurance available in this entire process.
FINRA BrokerCheck tells you the regulatory status, disclosures, and any documented history of customer complaints, arbitration awards, or disciplinary actions for broker-dealer professionals. The SEC’s Investment Adviser Public Disclosure database serves the same purpose for RIAs, and each adviser’s Form ADV Part 2 brochure spells out how they are paid, what conflicts they disclose, and what fees they charge. Read those three parts rather than the marketing summary. On CFP credentials, verify the individual rather than the firm.
Interpret what you find proportionately. An old settled arbitration from a firm the person left years ago is context, not a verdict. A current registration with no disclosures on a career spanning multiple firms is the ordinary, healthy result. Unresolved complaints, a revoked registration, or repeated disclosure patterns deserve an explanation before you proceed.
Ask for two references who resemble you: one roughly your age, one with a similar balance. Then ask the advisor for a client whose outcome they would rather you did not hear about. People who have handled a bad year with grace will tell you about it. People who have not will deflect.
Step 6: Interview several advisors with the same questions
Two or three candidates, the same script, the same notes. Comparing one interview to another is impossible unless the inputs match.
A workable structure: 10 minutes on their legal status and fees, 15 minutes on your specific situation, 10 minutes on process and communication, and 5 minutes for your questions. Take written notes during the meeting rather than after, because memory smooths over the caveats.
Score each candidate across five areas, one to five. Fiduciary and conflict transparency. All-in cost relative to your balance. Relevant experience with your type of situation. Communication cadence, judged against how often you actually want to talk. Chemistry and judgment, meaning whether you believe their answers. Then add the total and stop looking at how the conversation felt. Good conversation is not a reason to hire someone, though it does make the next five years easier.
Alongside the numbers, watch for a stated niche. Someone who works primarily with pre-retirees aged 55 to 70, or with business owners, has seen your exact mistake before. Someone who claims equal expertise across taxes, insurance, business succession and international trusts has probably handled each of those once.
Step 7: Check the agreement before hiring
Sign nothing in the meeting. Take the agreement home.
Read for these specific things: the exact services included, the fee schedule with any tier breaks, who holds custody and under what agreement, the account minimum, the review cadence, the termination terms on both sides, and how your data is handled. Then check that the signature block names individuals rather than only a firm, and that any arbitration clause or automatic renewal is written where you can see it.
One last distinction worth holding onto: a recommendation is advice, and your decision is yours. Any document that blurs those two is a document worth walking away from. New brokerage and investment-advisory agreements also carry a cancellation window, typically several business days, during which you can exit without a penalty. Know the deadline before you sign, not after.
Common Mistakes
Most people who are unsure how to choose a financial advisor fall into the same errors, and each one has a fix that prevents it.
- Sizing them up by assets under management. A firm managing billions has scale and a sales culture, neither of which predicts your service. Check whether the named advisor personally carries a reasonable number of households.
- Comparing the advertised fee instead of the all-in cost. Ask for the itemized total including fund expenses and any wrap fees. The headline number is marketing.
- Treating “fee-only” as a guarantee of a flat fee. Many fee-only RIAs charge an asset-based percentage anyway. The label describes compensation from products, not the shape of the bill. Ask for the schedule.
- Ignoring third-party compensation. Commissions on insurance and annuities can run for a decade. Ask what they earn when you follow the recommendation.
- Never checking the regulatory record. Ten minutes on BrokerCheck and Form ADV. A dismissal without an explanation is a rejection.
- Hiring without a written agreement. Verbal promises about services and fees are difficult to enforce and easy to forget.
- Attending only one interview. Every candidate sounds excellent alone. The comparison is where the differences show up.
- Failing to ask who serves the account later. Advisor turnover is common, and it should shape the decision.
- Being flattered into urgency. Retirement deadlines and tax windows are real, but almost no legitimate planning decision cannot wait a week.
Practical habits that make the rest easier: pay for a one-time plan first and see how the relationship feels before granting discretion; revisit at least every three years, or sooner after a major life change; keep your own copies of statements rather than relying on a portal; and check in annually whether the fee is still matched by the service level you are actually receiving.
Warning signs deserve a short list of their own. The first meeting is a sales appointment rather than a conversation about your situation. They cannot or will not say who they are paid by. They push a product before understanding what you are trying to do. They discourage you from checking their record. They make returns the main event. Any of those, on its own, is reason to keep looking.
Frequently Asked Questions
How do I know if a financial advisor is a fiduciary?
Ask directly, then confirm it in writing. A registered investment adviser owes you a fiduciary duty as a matter of law, which means putting your interest first and disclosing conflicts. A broker-dealer is held to a suitability standard instead. Confirm the status in the adviser’s Form ADV brochure and in your signed agreement, since some firms operate both models under separate entities.
How much does a financial advisor cost?
Asset-based fees commonly run from about 0.5 to 1.25 percent a year, often tiered by balance. Hourly planning often runs 200 to 400 dollars an hour, and a flat-fee written plan often falls between 2,000 and 7,000 dollars. Robo-advisors sit near 0.25 to 0.50 percent. Ask for the all-in figure, including fund expenses, because industry analyses put the average advised portfolio near 1.65 percent a year.
What is a typical fee for a fee-only fiduciary?
Most fee-only fiduciaries charge an asset-based percentage, often around 0.5 to 1 percent a year with tiered breakpoints. The term means they do not earn commissions on products, not that the bill is flat. Some fee-only planners charge by the hour or a flat fee instead. Since the label gets stretched in marketing, read the fee schedule rather than trusting the description.
Are robo-advisors better than human financial advisors?
For a simple, well-diversified portfolio, a robo-advisor often delivers the core value of an advisor cheaply: disciplined allocation, automatic rebalancing, and tax-loss harvesting, for roughly 0.25 to 0.50 percent a year. A human advisor earns its fee when your situation is genuinely complex, such as business ownership, equity compensation, multiple employer plans, or an estate to settle.
How do I check a financial advisor’s disciplinary record?
Search FINRA BrokerCheck for broker-dealer professionals and the SEC’s Investment Adviser Public Disclosure database for RIAs. Look for customer complaints, arbitration awards, and disciplinary actions, then check which firm the person was with at the time. Verify CFP credentials with the individual rather than the firm. Ten minutes of reading here protects years of fees.
How do I switch financial advisors without losing money?
Move assets directly, account to account, between custodians rather than withdrawing cash and sending it somewhere. Ask the new custodian for transfer forms so the transfer happens in securities without a sale. Watch for surrender charges on annuities, and never accept an unsolicited rollover offer, since that carries costs and usually benefits whoever suggested it.
Conclusion
Start with a single page of your own: goals, accounts, costs, and what you want someone to handle. Then interview two or three qualified advisors with the same questions, the same fee comparison, and the same scorecard, and read each regulatory record before the second meeting. That is how to choose a financial advisor without letting anyone rush you, and the whole process takes a few evenings. It protects every year that follows. If the answer along the way is that a simple index portfolio and no advisor serves you better, that is a legitimate result too.