A safe withdrawal rate is the percentage of your retirement portfolio you can take out each year, then raise for inflation, without the money running out before you die. There is no single number that works for everyone, so this guide walks through the main strategies, what each one assumes, and how your asset mix and other income change the math.
Most of the confusion around retirement income comes from mixing up two different things. A withdrawal rate is a planning tool — a hypothesis you stress-test against decades of market data. A spending rate is a decision about how you actually live. Keeping them separate makes the whole planning process calmer, because you can adjust one without pretending the other is permanent.
What follows is education, not personal investment, tax, or legal advice. Rules, rates, and thresholds change, and they vary by state and situation, so treat every figure here as a starting point to check against your own numbers with a qualified professional.
Table of Contents
- What Is a Safe Withdrawal Rate?
- What a 90% or 95% success rate actually means
- How Much Can You Withdraw Each Year?
- Where the numbers came from
- Safe Withdrawal Rate Strategies Explained: How Each Works
- The 4% rule: fixed and inflation-adjusted
- Conservative fixed rates: 3% to 3.5%
- Guardrails: cut spending, then restore it
- Dynamic and portfolio-based withdrawals
- Essential-spending floors
- Flexible spending: base pay plus bonus
- Required minimum distributions as a strategy
- Bucket strategy
- What the strategies mean in practice
- A guardrails walkthrough on a 1 million-dollar portfolio
- How Does Investment Mix Affect Withdrawal Safety?
- How Can You Make Withdrawals More Flexible?
- Common Mistakes That Can Break a Withdrawal Plan
- How to Build a Withdrawal Strategy Step by Step
- 1. Estimate essential spending
- 2. Inventory income that does not depend on markets
- 3. Pick a starting rate based on your horizon
- 4. Stress-test three market paths
- 5. Choose your flexibility rules in advance
- 6. Set the withdrawal order and tax plan
- 7. Review on a schedule
- Frequently Asked Questions
- Is the 4% rule still safe for retirees?
- How much can I safely withdraw from my retirement savings?
- Can I reduce withdrawals when the market declines?
- How often should I review my retirement withdrawal strategy?
- How does Social Security affect my safe withdrawal rate?
- Conclusion
What Is a Safe Withdrawal Rate?
A safe withdrawal rate is the share of your retirement savings you can withdraw annually, adjusted for inflation, without depleting the portfolio over your expected retirement. You set the percentage once, based on your starting balance, and the strategy is judged by whether the money survives the full retirement.
Two details matter more than most people expect. First, the rate is almost always applied to the starting portfolio value, not the current balance. Second, the dollar amount goes up each year with inflation, so your withdrawal rises from year to year while the percentage stays the same. That is what makes the 4% rule different from simply taking 4% of whatever you happen to have left.
Most published rates assume a 30-year retirement. Retiring at 55 gives you 40-plus years of withdrawals, and a 45-year horizon usually supports a noticeably lower rate than a 25-year one.
What a 90% or 95% success rate actually means
Researchers run the same strategy across hundreds or thousands of historical and simulated market paths and count how often the money lasted. A 95% success rate means the portfolio survived in 95 out of 100 modeled histories. It is not a promise about your particular future, and in the failed 5 the money usually runs out in the last decade rather than all at once.
Most rates in circulation come from 30-year studies built on historical U.S. data, mostly from the era when bond yields were far higher than they are now. That starting point is one reason retirement forum readers often say the 4% rule feels dated. Low bond yields support a lower sustainable rate, and starting valuations matter too, because a portfolio bought at a high multiple has less room for error.
How Much Can You Withdraw Each Year?
The rate you pick sets the portfolio you need, and the relationship runs backwards: every step up in the withdrawal rate requires a meaningfully larger pile of savings. On a 500,000-dollar portfolio, the difference between a conservative rate and an aggressive one is 10,000 dollars a year in spending, plus the higher risk of running short.
| Starting withdrawal rate | Annual withdrawal on a 500,000-dollar portfolio | Portfolio needed for 60,000 dollars of income | Best fit |
|---|---|---|---|
| 3.0% | 15,000 dollars | About 2,000,000 dollars | Long horizons, early retirees, near-certain success |
| 3.5% | 17,500 dollars | About 1,710,000 dollars | 40-year retirements, legacy-focused households |
| 4.0% | 20,000 dollars | About 1,500,000 dollars | The classic 30-year benchmark |
| 4.5% | 22,500 dollars | About 1,330,000 dollars | Retirees with pension or Social Security offsets |
| 5.0% | 25,000 dollars | About 1,200,000 dollars | Short horizons or large other income |
None of these rates is guaranteed. The table shows the arithmetic, and the arithmetic is the part readers most often get wrong.
Where the numbers came from
Bill Bengen published the study that produced the 4% rule in 1994, testing a portfolio of equities, bonds, and cash against rolling 30-year periods and asking how much a retiree could have taken without going broke. He later revisited the data with updated assumptions and landed closer to 4.5% for the highest-survival rates, which is why you see ranges like 4.5% to 4.7% in more recent work.
Retirement age moves the range a lot. Monte Carlo work summarized by Covenant Wealth Advisors, run on a 1 million-dollar IRA with a 20 percent tax rate, put the median sustainable rate near 2.5% to 3.0% for someone retiring at 55, 3.4% to 3.8% at 65, and 5% or more at 70. Those figures depend on the allocation and the assumptions behind them, so read them as a direction rather than a verdict.
The reverse calculation matters too. Readers on r/Fire regularly ask why cutting the assumed rate pushes their savings target so much higher, and the answer is the division: at 3.5%, a 60,000-dollar lifestyle needs roughly 1.71 million dollars, while at 4.0% it needs 1.5 million. A half-point is about 210,000 dollars of extra savings.
Safe Withdrawal Rate Strategies Explained: How Each Works
Every strategy below is a set of rules for turning a portfolio into annual income. They differ in one main respect: what happens to your spending when markets go badly.
The 4% rule: fixed and inflation-adjusted
Withdraw 4% of the starting balance in year one, then add inflation every year after. If your portfolio was 500,000 dollars and inflation runs 2.5% a year, the second-year withdrawal is 20,500 dollars, the third is 21,012.50, and so on.
The appeal is that you never have to touch the principal target again or re-decide anything under pressure. The cost is that it ignores reality. A retiree who spent 30,000 dollars in a weak year and 150,000 in a strong one — the pattern described by an r/Fire user planning to spend down a 2 million-dollar portfolio — is living quite differently from the flat spender the rule assumes.
Conservative fixed rates: 3% to 3.5%
Same mechanics, lower starting percentage. You give up spending now in exchange for a wider margin against bad sequences, a longer horizon, or a larger bequest. This is the default I would look at first for a 40-year retirement or a household that wants the portfolio to outlive them.
Guardrails: cut spending, then restore it
The Guyton-Klinger method sets an initial withdrawal rate and then watches it. If the withdrawal you are taking rises to 20% or more above that initial rate, you cut spending by 10% and reset the initial rate lower. If it falls to 20% or more below, you raise spending by 10% and reset higher.
Dynamic and portfolio-based withdrawals
Rather than fixing a percentage, a dynamic strategy sets each year’s dollar amount from the current balance, applying a rate that rises as you get older and the horizon shortens. Wade Pfau and Michael Kitces have written about this family of methods extensively. The appeal is that spending naturally follows market conditions; the drawback is that it can produce uncomfortable volatility in your income from year to year.
Essential-spending floors
Split your spending into a floor you will not touch and a flexible layer on top. The floor gets funded from income you can count on — Social Security, a pension, coupons, rent from a small property — and the portfolio covers everything else. The strategy converts part of your portfolio problem into a fixed-income problem.
Flexible spending: base pay plus bonus
Set a base withdrawal that covers essentials and treat the rest as a bonus paid out of portfolio gains. Bradley Clark’s version uses a 3% base and a 4% rate after two consecutive 10% growth years, which keeps annual income steadier than a percentage-of-balance method.
Required minimum distributions as a strategy
Once you reach the age where the IRS requires distributions, that number sets a floor you cannot opt out of. Using RMDs as your withdrawal method is simple and often produces higher income early, but Morningstar’s comparison found it carries the highest cash-flow volatility of the four flexible methods it tested and the lowest median ending value. Below RMD age it does nothing at all, so it cannot be the whole plan.
Bucket strategy
Split the portfolio into buckets — near-term cash and short bonds, mid-term bonds, long-term equities — and refill them as they drain. It smooths the sales schedule so you are not forced to sell a large block of equities in a crash. RBC Wealth Management includes this income-only and bucket framing among its down-market protections.
What the strategies mean in practice
The table shows how each rule set behaves across four situations.
| Strategy | Starting rate | Income in good markets | Income in poor markets | Legacy impact |
|---|---|---|---|---|
| 4% rule | About 4% | Flat, inflation-adjusted | Flat, no help | Moderate |
| Conservative fixed | 3% to 3.5% | Flat, lower | Flat, no help | Higher |
| Guardrails | About 4% | Rises when markets run | Cuts by 10% | Moderate to high |
| Dynamic | 3.5% to 4.5% | Rises with balance | Falls with balance | Varies |
| Essential floor | Portfolio covers the gap | Steady base income | Steady base income | Higher |
| Base plus bonus | 3% base, 4% bonus | Lumpy, larger | Base only | Moderate |
| RMD framework | Set by tax rules | Rises in your 70s and 80s | Falls in a down year | Lower |
| Bucket | About 3.5% to 4% | Steady | Smoothed by cash buckets | Moderate |
A guardrails walkthrough on a 1 million-dollar portfolio
Take a retiree who needs 40,000 dollars a year from a 1 million-dollar portfolio. The initial withdrawal rate is 40,000 divided by 1,000,000, or 4.0%. The illustration below freezes the dollar amount so the triggers are visible; a real plan would also add an inflation adjustment each year.
| Year | Market move | Balance after withdrawal | Withdrawal | Current rate vs initial 4.0% | Action |
|---|---|---|---|---|---|
| 1 | -10% | 864,000 | 40,000 | 4.63% | None, under the 4.8% trigger |
| 2 | -10% | 741,600 | 40,000 | 5.39% | Cut 10% to 36,000, new initial rate 4.85% |
| 3 | +10% | 779,760 | 36,000 | 4.62% | None |
| 4 | +10% | 821,736 | 36,000 | 4.38% | None |
| 5 | +10% | 867,910 | 36,000 | 4.15% | None |
| 6 | +10% | 918,701 | 36,000 | 3.92% | None |
| 7 | +10% | 974,571 | 39,600 | 4.06% | Raise 10% once the rate fell below 3.88% |
That is the trade in plain numbers. Two bad years cost 4,000 dollars a year, and seven years of good returns gave most of it back. The value of the method is that the cut happened on a rule rather than on panic, which is when most people make their worst decisions.
How Does Investment Mix Affect Withdrawal Safety?
Your allocation determines how much of your income you can take without touching principal, and how violently that income moves when markets turn.
Equities have delivered the best long-run returns, which is why they support the highest withdrawal rates, but they can drop 20% or more in a year with little warning. Bonds and cash add stability and income, and they are what let you sell less during a decline.
That is sequence-of-returns risk in one sentence: a portfolio that falls early has less time and less capital to recover, while the same sequence in year 25 matters far less. This is why the first decade dominates outcomes, why retirees who leave the workforce at 55 face a different problem than those who leave at 65, and why many early retirees hold two to three years of planned spending in cash and short bonds as a buffer to avoid selling equities at the bottom.
Account type changes the arithmetic too. Withdrawals from taxable accounts can create capital gains and a lower tax rate on the portion above your ordinary income brackets, while traditional accounts produce ordinary income taxed at your marginal rate and Roth accounts are tax-free if you have complied with the required minimum distribution rules for five years. Which order makes sense depends on your bracket, your balances, and your state. RMDs add a hard constraint: from the age when they begin, the tax code sets a floor on what you take out, whether your plan calls for it or not.
Long-term retirees can cut back on equities near the end, since the last decade of a portfolio is mostly about funding income rather than growth. As the horizon shortens, most frameworks shift allocation toward bonds and cash. None of this is a recommendation for your portfolio; it is a description of why the rates move.
How Can You Make Withdrawals More Flexible?
Most withdrawal plans fail on spending behavior, not on math. The households that last longest are usually the ones that can cut a discretionary layer in a bad year without touching the essentials.
Start by splitting your annual spending into three columns: needs, wants, and future goals. Protect the first, flex the second, and fund the third last. A retiree cutting 20 percent of a 60,000-dollar budget has to find it almost entirely in the flexible column, and that is a very different conversation from cutting across the board.
Then look at the income that is not your portfolio. Social Security at 62 differs meaningfully from the same benefit claimed at 70, and it adjusts for inflation each year, which makes it a natural hedge against a bad equity decade. A pension, an annuity with a lifetime benefit, or rental income does similar work by turning portfolio risk into a fixed obligation. A r/Fire poster with an 80,000-dollar benchmark on a 2 million-dollar nest egg and a die-with-zero mindset has built in exactly this kind of flexibility, planning on 30,000-dollar years and 150,000-dollar years. Forum threads on r/leanFIRE and r/ChubbyFIRE show the same instinct in less aggressive form.
Decide your withdrawal order before you need it. Sorting accounts by tax efficiency usually puts taxable assets first, then tax-deferred balances, then Roth money, though the right order flips depending on bracket, expected returns, and whether you expect a tax cut or a larger bequest. Long-horizon retirees on r/ExpatFIRE raise a version of the same problem — with 50 or 60 years of spending ahead, a percentage-of-balance rule stays uncomfortable almost the entire time.
Finally, let expected spending fall as you age. EBRI spending-pattern research shows spending declines by roughly 19 percent between ages 65 and 75, 34 percent between 65 and 85, and 52 percent between 65 and 95. Most fixed-rate strategies model a spender who never changes, and that assumption quietly inflates the portfolio you think you need.
Common Mistakes That Can Break a Withdrawal Plan
- Treating 4% as a guarantee. It is a historical average from a specific period, not a promise. Fix: plan at a rate you would be comfortable repeating if markets behave badly, and stress-test it against the worst sequences in your data.
- Ignoring inflation. A flat 20,000 dollars a year is a shrinking income in real terms over 30 years. Fix: build the annual inflation adjustment into the rule before you start, not after spending erodes.
- Spending more in the early years. Early retirement is when spending is highest, which is exactly when the portfolio is smallest and most exposed. Fix: set a first-year ceiling you can live with through a full drawdown and treat raises as earned rather than scheduled.
- Withdrawing through a decline with no plan. Panic selling in a bear market converts a temporary loss into a permanent one. Fix: hold two to three years of spending in cash and short bonds, and write down the triggers for selling equities in advance.
- Relying on one income source. Depending entirely on portfolio withdrawals puts all your eggs in the market basket. Fix: convert part of the balance into income that arrives whether markets cooperate or not.
- Changing your allocation every year. Rebalancing too often raises costs and taxes and adds noise. Fix: rebalance on a set schedule or at fixed thresholds, and keep the equity share within the range your horizon supports.
- Forgetting taxes and required minimum distributions. A pre-tax 4% is not a 4% in your pocket, and RMDs can force a year of income you did not plan. Fix: run the plan after tax and check the RMD age on the horizon.
- Never revisiting the plan. A strategy set at 60 is wrong by 70. Fix: schedule a short annual review and a fuller one every three years.
How to Build a Withdrawal Strategy Step by Step
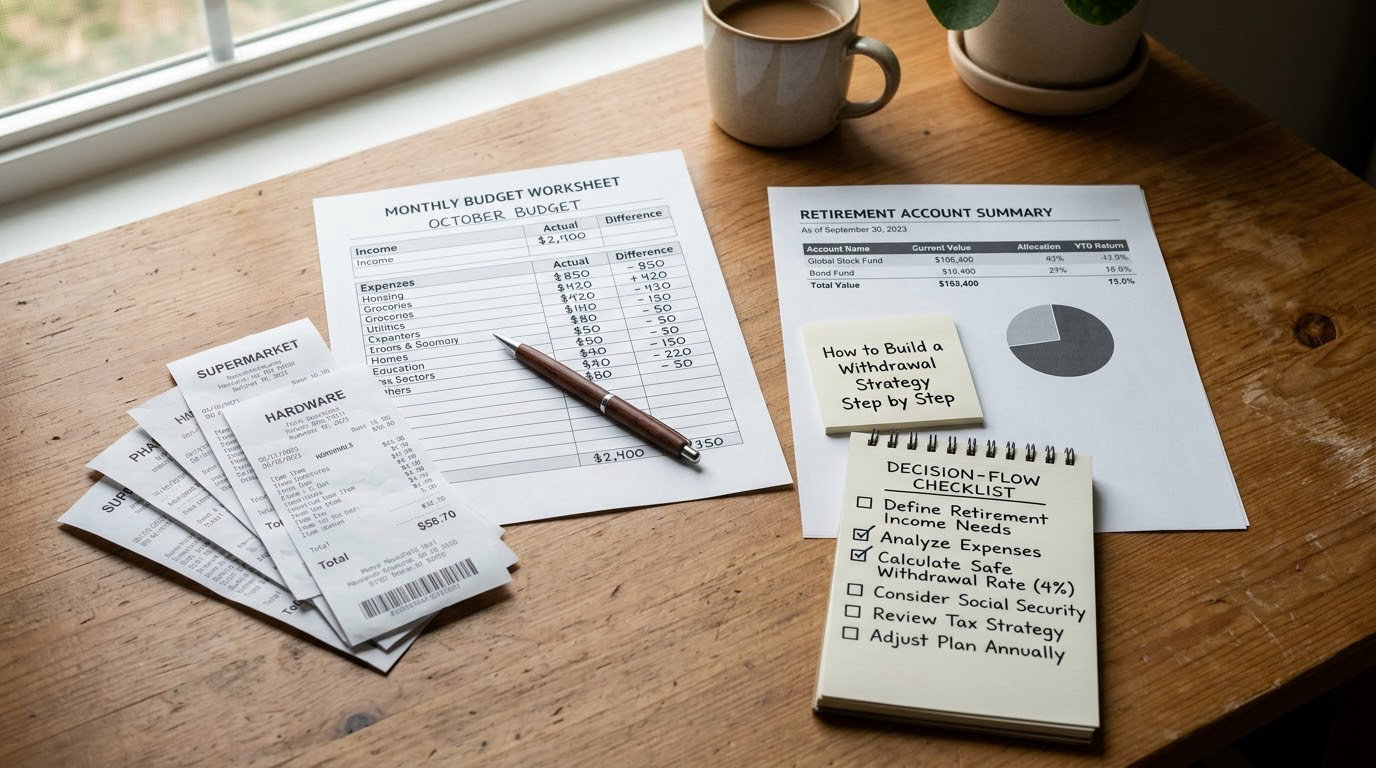
Building a plan takes one spreadsheet and an afternoon. The order below matters, because each step produces the input for the next one.
1. Estimate essential spending
List the last twelve months of actual household spending and sort it into needs and wants. Success looks like a needs number you would defend in a bad year without thinking about it.
2. Inventory income that does not depend on markets
Add Social Security at the claiming age you actually intend, any pension, and expected interest or dividends. Success is a single dollar figure showing how much the portfolio must cover.
3. Pick a starting rate based on your horizon
Use your age at retirement, not your current age. Subtract guaranteed income, divide the remainder by your portfolio, and check whether the percentage lands near your age band. Success is a rate between 3% and 4% for a 30-year retirement, lower if your horizon is longer.
4. Stress-test three market paths
Run a normal path, a path with two consecutive down years at the start, and a path with high inflation and weak equity returns. Success is a plan where the bad path forces a spending cut, not a permanent change of strategy.
5. Choose your flexibility rules in advance
Decide now what you cut first, how much, and what triggers a cut. Write it where you will find it in February of a bad year. Success is knowing the answer before you need it.
6. Set the withdrawal order and tax plan
Decide which accounts fund spending, when a Roth conversion is worth doing, and how RMDs change the schedule. Success is a documented order rather than an improvisation.
7. Review on a schedule
Once a year, check spending against the plan and rebalance within thresholds. Every three years, rerun the projection with actual values. Success is small corrections on a fixed date instead of a full rethink after every market swing.
Frequently Asked Questions
Is the 4% rule still safe for retirees?
The 4% rule is still a useful benchmark, but it is no longer automatically conservative. It came from 30-year studies built largely on 1990s data, when bond yields were much higher and valuations were lower. Later research by Bengen and others put higher-survival rates closer to 4.5% to 4.7%, which suggests a cautious retiree today should look at 3.5% to 4% as a starting range rather than assuming 4% leaves comfortable margin.
How much can I safely withdraw from my retirement savings?
Start by dividing your annual spending need, minus Social Security and any pension, by your portfolio value. That gives your starting rate, and the number you land on is what the strategy analysis tests. On a 500,000-dollar portfolio, 3% supports 15,000 dollars a year, 4% supports 20,000, and 5% supports 25,000. Lower your rate for a longer horizon or a larger bequest goal.
Can I reduce withdrawals when the market declines?
Yes, and having a written rule for it is one of the best things you can do. Guardrails strategies cut spending by 10% when your withdrawal rate rises to 20% above the initial rate, then restore it when conditions improve. The point is not the cut itself, which costs you real money, but making the cut on a rule instead of on panic during a volatile year.
How often should I review my retirement withdrawal strategy?
A light annual check is enough most years: confirm your spending matches the plan and rebalance within set thresholds. Every three years, rerun the projection with your actual balances, actual spending, and current assumptions, because a decade of lifestyle changes can move your needs by a lot. Revisit sooner if you retire, sell the house, or a large medical bill changes the shape of your spending.
How does Social Security affect my safe withdrawal rate?
Social Security reduces the amount your portfolio has to produce, so it lowers the withdrawal rate your nest egg needs to support. Because the benefit is inflation-adjusted and arrives regardless of market conditions, it also reduces the risk of having to sell equities during a decline. Claiming age matters, since taking it earlier permanently raises the monthly benefit, which means fewer dollars are left for the portfolio to cover.
Conclusion
No single safe withdrawal rate fits every retirement, and the strategies that look safest in a spreadsheet differ in how they behave in a bad year. Your first three moves are unglamorous and they matter more than the rate debate: separate essential spending from discretionary spending, add up the income that arrives whether markets cooperate or not, and then test the resulting percentage against several market scenarios.
If a starting rate is going to stress you, start a percentage lower than the research supports and let guardrails rules give some back in strong years. That is a far more common outcome than running out of money, and it is the one worth planning for.