Most people need about 25 times their expected annual retirement expenses to retire comfortably, or roughly 10 to 12 times their final pre-retirement salary by the time they reach 67. That means a couple who spends $80,000 a year in retirement is looking at a $2 million nest egg, and a single retiree spending $50,000 a year needs closer to $1.25 million.
Those two anchors are the starting point, not the answer. Your actual number depends on when you stop working, how much Social Security and pension income fills the gap, what healthcare costs you in your sixties and seventies, and how long the money has to last. This guide walks through the calculation step by step so you can replace the multiples with your own numbers.
Table of Contents
- Retirement Costs and Income at a Glance
- The four rules of thumb, and why they all point the same way
- How much you should have saved by age
- Worked examples at four income levels
- What Affects the Amount You Need to Retire
- Retirement age and how long the money has to last
- Is $1 million enough to retire?
- Social Security, pensions and part-time work
- Healthcare, Medicare and long-term care
- Housing, location and the rest of the budget
- Returns, inflation and sequence of returns risk
- Taxes on retirement income
- Life expectancy
- How to calculate your own number
- Ways to Save
- Start earlier, even with small amounts
- Take the full employer match
- Use tax-advantaged accounts in the right order
- Pay down high-interest debt
- Retire later or work a little longer
- Reduce spending deliberately
- Recheck the plan every year
- Frequently Asked Questions
- Can I retire at 60 with $500K in savings?
- What is a good 401k balance at age 65?
- Is $2 million enough to retire on?
- At what age can I retire comfortably with $1 million?
- Can I retire at 45 with $3 million?
- How much do you really need to retire early?
- Conclusion
Retirement Costs and Income at a Glance
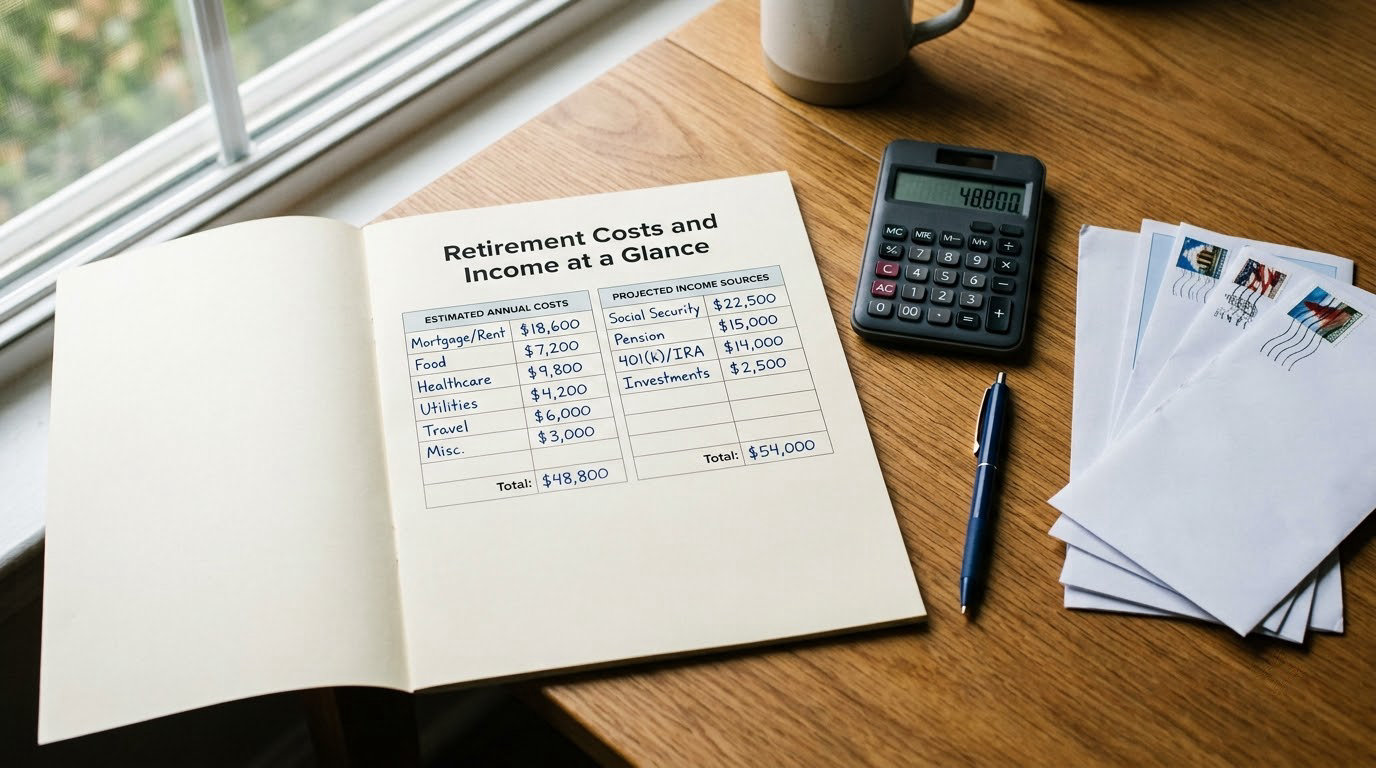
Retirement spending is usually lower than your working years, mostly because payroll taxes stop and retirement saving ends. AARP research has long pointed to replacing roughly 70% to 80% of pre-retirement income to maintain a similar standard of living. Plenty of retirees need far less, especially once a paid-off home and no work commute are factored in. Others need the full amount or more, because travel, private health coverage and grandchildren are not free.
The table below is a set of illustrative US household estimates you can overwrite with your own. These are typical planning ranges, not survey averages, and they vary widely by region, household size and health.
| Retirement spending category | Lean | Comfortable | High |
|---|---|---|---|
| Housing (mortgage or rent, taxes, insurance, upkeep) | $18,000 | $30,000 | $55,000 |
| Health: premiums, Medicare, prescriptions, out-of-pocket | $9,000 | $16,000 | $28,000 |
| Food and groceries | $7,000 | $10,000 | $14,000 |
| Transportation | $6,000 | $10,000 | $18,000 |
| Utilities and internet | $5,000 | $8,000 | $12,000 |
| Insurance: life, umbrella, long-term care | $2,000 | $5,000 | $12,000 |
| Travel, hobbies and giving | $4,000 | $12,000 | $30,000 |
| Total annual spending | $51,000 | $91,000 | $169,000 |
The four rules of thumb, and why they all point the same way
- 25x rule. Multiply annual retirement expenses by 25. Spending $60,000 a year implies $1.5 million invested.
- 4% rule. The same math stated backwards. Withdraw 4% of a portfolio in your first retirement year, adjust for inflation each year afterward, and the money is designed to last 30 years.
- 70% to 80% income replacement. Aim to replace roughly three-quarters of your pre-retirement income, because savings replace the salary you stopped earning.
- 10x to 12x final salary. A quick proxy when you have not built a budget: a $100,000 earner aims for $1 million to $1.2 million at 67.
These are not competing rules. The 4% rule is the inverse of the 25x rule, because dividing one by 0.04 gives you twenty-five. The salary multiple works because retirees typically replace 70% to 80% of income and that salary itself was roughly 25% of income after taxes.
How much you should have saved by age
Fidelity publishes the age-banded salary multiples below, and every other outlet repeats them because the math is sound. Treat them as checkpoints. A self-employed person with no employer match or someone carrying student debt will sit below the line, and that is a reason to adjust the plan rather than accept the gap.
| Age | Salary multiple to have saved | Example on a $90,000 salary |
|---|---|---|
| 30 | 1x | $90,000 |
| 35 | 2x | $180,000 |
| 40 | 3x | $270,000 |
| 50 | 6x | $540,000 |
| 55 | 7x | $630,000 |
| 60 | 8x | $720,000 |
| 67 | 10x | $900,000 |
Worked examples at four income levels
These assume a comfortable retirement spending level of about 80% of pre-retirement income, Social Security claimed at 67, and a 25x multiplier on the remainder.
| Pre-retirement salary | Retirement spending target | Less Social Security (typical) | Portfolio needed | Total nest egg |
|---|---|---|---|---|
| $50,000 | $40,000 | $17,000 | $575,000 | About $750,000 |
| $75,000 | $60,000 | $22,000 | $950,000 | About $1.2 million |
| $100,000 | $80,000 | $26,000 | $1.35 million | About $1.6 million |
| $150,000 | $120,000 | $32,000 | $2.2 million | About $2.5 million |
Social Security figures are rough planning estimates based on a long working career at steady wages. Yours will differ based on your birth year, contribution history and claiming age.
What Affects the Amount You Need to Retire
Once you have a baseline spending figure, the variables below do most of the work in moving your number up or down.
Retirement age and how long the money has to last
This is the biggest lever you control. A 30-year retirement is materially easier to fund than a 45-year one, and the safe withdrawal rate has to fall as the horizon lengthens. Early retirement communities settled on 3% to 3.5% for a 40-plus year plan for good reason.
| Annual spending | 20-year horizon | 25-year | 30-year | 40-year |
|---|---|---|---|---|
| Withdrawal rate used | 4.5% | 4.25% | 4.0% | 3.25% |
| $40,000 per year | $890,000 | $940,000 | $1,000,000 | $1,230,000 |
| $60,000 per year | $1,330,000 | $1,410,000 | $1,500,000 | $1,850,000 |
| $80,000 per year | $1,780,000 | $1,880,000 | $2,000,000 | $2,460,000 |
| $100,000 per year | $2,220,000 | $2,350,000 | $2,500,000 | $3,080,000 |
Read that table by row and it answers most of the “can I retire at 60” questions people search. At 60 with a 25-year horizon and a 4.25% rate, $500,000 supports about $21,000 a year before Social Security.
Is $1 million enough to retire?
At a 4% withdrawal rate, $1 million supports about $40,000 a year for thirty years in today’s dollars. Retire at 65 with a household spending plan near $50,000, plus Social Security, and it works for many people. Retire at 45 in a high-cost city with no pension and the same million covers considerably less ground.
Social Security, pensions and part-time work
Social Security is the largest income source for most retirees. Claiming at 62 rather than 67 raises the monthly payment permanently but cuts the lifetime total for anyone who lives past the early eighties. Waiting until 70 gives the largest monthly check of all. Model your own estimate at ssa.gov and subtract it from spending before you size the portfolio.
A defined-benefit pension nets out the same way. Take the annual pension you will actually receive, discount it for taxes, and subtract it from your spending target. There is no need to hit a savings benchmark on top of income you are already guaranteed.
Part-time work, a small consulting income or rental income count too, though treat them conservatively. Rentals carry maintenance, vacancy and tax costs that rarely show up in a spreadsheet.
Healthcare, Medicare and long-term care
Healthcare is the cost most often left out of retirement budgets, and it is the one that most often breaks them. Before Medicare kicks in at 65, premiums and out-of-pocket costs can run into the tens of thousands a year. After 65, Medicare Part B premiums, supplement policies, prescriptions and hearing and dental coverage add up steadily.
The uncomfortable line item is long-term care. Private room nursing care can exceed $100,000 a year depending on your area, and neither Medicare nor most health plans cover it. A long-term care policy bought in your fifties, a dedicated care fund, or an explicit decision to plan for family care are the three routes people take.
One more gotcha: if your nest egg is large, Medicare Part B and Part D premiums can rise through the IRMAA surtax. A balance in the seven figures can push you into higher premium brackets, which is worth pricing into a high-balance plan.
Housing, location and the rest of the budget
Your home is usually the biggest single line. Paying off a mortgage before retirement removes a large fixed cost entirely, and moving to a lower-cost region or a smaller home after a move can cut spending by $10,000 a year or more without touching your lifestyle in a way you hate. State income tax, property tax and insurance vary enormously, so the same lifestyle costs different amounts in different places.
Debt matters too. Car payments, credit card balances and student loans all compete with the withdrawal. A retiree who clears high-interest debt before stopping work gains far more than someone who chases an extra 0.5% of return.
Returns, inflation and sequence of returns risk
Your projection needs a return assumption and an inflation assumption. Most planners use something in the 4% to 5% range for real returns on a balanced stock and bond portfolio during accumulation, then step the withdrawal rate down for a longer retirement. Note the word real, meaning after inflation. Quoting a 7% nominal return against a 3% inflation rate without saying so is how people build optimistic plans by accident.
Sequence of returns risk is the danger that the first decade goes badly. If withdrawals begin in the same stretch as a 30% market decline, the portfolio has to sell shares low to pay bills, and the recovery never fully happens. The historical studies that produced the 4% rule were done on portfolios that survived exactly this test, which is why a bad first decade is worth planning around rather than dismissing.
Taxes on retirement income
Money in a traditional 401(k) or IRA is taxed as ordinary income on withdrawal. Roth money is not, and that difference is large across three decades. Required minimum distributions in your seventies can force taxable income even if you do not need the cash. Across a long retirement, spreading withdrawals across taxable, tax-deferred and tax-free accounts usually lowers lifetime taxes, and a Roth conversion ladder in the years before Medicare and RMD rules tighten is a common way to manage it.
Life expectancy
Plan for longer than feels reasonable. Reaching 90 is not rare, and a plan that dies at 85 is a plan that ran out of money. The flip side is that longevity risk is why most retirees delay claiming Social Security to 70, since the larger payment continues for life.
How to calculate your own number
You can do this in five steps with a phone calculator. No spreadsheet software, no advisor required.
- Estimate annual retirement spending. Take your current after-tax spending, remove work-specific costs like commuting and payroll taxes, and add back what you actually want to spend on travel and hobbies.
- Subtract reliable income. Deduct your Social Security estimate, pension income in dollars, and a modest allowance for part-time work.
- Divide by your withdrawal rate. Use 4% for a 25 to 30 year retirement, 3.5% for a 35 year horizon, 3% to 3.25% for 40-plus years.
- Adjust for taxes and known costs. Consider whether the remaining portfolio is pre-tax, tax-deferred or Roth, and add a healthcare line if Medicare is a decade away.
- Compare to what you have. The difference between your target and your current balance, divided by your years remaining until retirement, is roughly what you need to save or invest each year.
That last step is where the real answer to how much do you need to retire takes shape. It turns a vague worry into an annual savings figure you can act on this month.
Ways to Save
Every dollar you do not need in retirement is a dollar you do not have to save for it. These are the levers that move the number most reliably.
Start earlier, even with small amounts
Compounding does most of its work when the money has decades to grow. Someone contributing 5% of a modest salary at 25 arrives at 65 with more than twice the balance of someone who starts at 45, purely on time in the market. If you have delayed, the arithmetic is still workable, just more concentrated in fewer years.
Take the full employer match
A 50% match on 6% of pay is an immediate 50% return on that contribution. Nothing else in your plan comes close, and it is the step people skip when they set up payroll and never revisit it.
Use tax-advantaged accounts in the right order
Starting with any employer match in a 401(k), then a traditional IRA for the deduction if you qualify, then a Roth IRA for tax-free growth, then back to the 401(k) to reach the annual contribution limit is the usual order. If you are 50 or older, catch-up contributions raise that limit and are worth using in full.
Pay down high-interest debt
Credit card interest at 20% is a guaranteed loss. Eliminating it while you still have wages is one of the highest-return moves available, and it protects the portfolio from sequence-of-returns damage later.
Retire later or work a little longer
Two extra years of saving adds years of contributions and shortens the drawdown period by two, which cuts the required withdrawal rate. Part-time work for two or three years before full retirement does the same thing without touching the portfolio.
Reduce spending deliberately
Trimming $10,000 of annual spending cuts $250,000 off a 25x target. The big levers are housing, vehicles and recurring subscriptions. Downsizing, driving an older car and cancelling rarely used memberships produce more than skipping coffee.
Recheck the plan every year
Spending changes as you approach retirement, and so does your income. Once a year, rewrite your spending estimate and re-run the calculation. It takes an hour and it catches drift long before it becomes a crisis.
These are general planning ideas rather than individualized financial advice. Rules, tax rates, benefit formulas and contribution limits change over time, and a fee-only financial advisor or tax professional can help you apply them to a specific situation.
Frequently Asked Questions
Can I retire at 60 with $500K in savings?
At a 4% withdrawal rate, $500,000 supports about $20,000 a year, rising with inflation each year for a 25-year retirement. Add Social Security claimed at 67 and a lean spending budget, and it works as a bridge retirement for a single person. It does not replace a full income, and anyone without a pension should plan on a withdrawal rate near 3.5% to 3.75% given the horizon.
What is a good 401k balance at age 65?
Fidelity’s benchmark puts the age 65 target at roughly 10 times your final salary, so a $100,000 earner aims for about $1 million by 67. It is a guideline for tracking progress rather than a rule. If you are behind, the useful question is the annual contribution required to close the gap over your remaining years, not whether the benchmark itself can still be hit.
Is $2 million enough to retire on?
At a 4% rate, $2 million supports about $80,000 a year for thirty years before Social Security and taxes. For a couple pre-tax that is comfortable. It gets tighter for high earners retiring before 60 without a pension, for anyone expecting significant long-term care costs, or for a retirement that needs to fund forty-plus years.
At what age can I retire comfortably with $1 million?
It depends almost entirely on your spending plan and horizon. A $1 million portfolio withdraws about $40,000 a year at 4%, so retiring at 65 with spending near $50,000 plus Social Security is reasonable. At 55 you would target roughly 3.75% to 4%, and at 45 closer to 3% to 3.5%, with healthcare bridged until Medicare.
Can I retire at 45 with $3 million?
At 3.5%, $3 million supports about $105,000 a year for forty years; at 4%, closer to $120,000. Whether that is enough depends on your housing, health coverage and state taxes. Sequence-of-returns risk is the real threat, so many people at that level hold two to three years of spending in cash to avoid selling during a crash.
How much do you really need to retire early?
Retiring early means a longer horizon, which demands a lower withdrawal rate. Instead of 25x expenses at 4%, plan on 30x to 33x, or 3% to 3.25%, to cover a forty-plus year retirement. You also need to fund health insurance until you reach Medicare age, often the most underestimated cost in early retirement plans.
Conclusion
Start with a number: write down what you would actually spend in a year, subtract your Social Security and pension estimates, and divide the remainder by a withdrawal rate that matches how long the money has to last. That figure is the real answer to how much do you need to retire, and it will almost certainly differ from the rule of thumb you had in mind.
Then review it once a year as your spending, benefits and balance change. Benefits formulas, tax rules and healthcare costs shift over time, so treat every figure in this guide as a planning estimate to re-check rather than a permanent fact.