Most RMD tax surprises are not caused by a bad withdrawal. They are caused by a good withdrawal that nobody planned for. A required minimum distribution is the minimum the IRS requires you to take from a pre-tax retirement account once you reach a set age, and it lands on your tax return as ordinary income in the same year you take it. You cannot shrink the required amount, but you can control almost everything around it: which accounts are covered, when the money moves, how much tax is withheld, and whether you spent years preparing for the bill. Here is how to avoid RMD tax surprises by handling the whole thing in order rather than in the last week of December.
This checklist takes about two hours the first time and twenty minutes a year after that. You need current statements, your prior-year tax return, and a rough idea of what you spent and earned this year. Everything below applies to US retirement accounts only, and the rules shift with legislation, so treat the figures as a starting point and confirm them against current IRS guidance before you move money.
One framing matters more than anything else in this article. The RMD amount is fixed by statute and a life expectancy table. The tax created by that amount is not fixed, and that is the part you manage.
Table of Contents
- What You Need
- Step-by-Step: How to Avoid RMD Tax Surprises
- 1. Identify Every Account That May Require an RMD
- 2. Confirm Your Age and Whether an Exception Applies
- 3. Calculate the Correct Distribution Amount
- 4. Review the Deadline and Plan the Payment
- 5. Estimate the Tax and Withholding Consequences
- 6. Check for Taxes That Are Not Automatically Withheld
- 7. Keep Records and Reconcile the Distribution
- Common RMD Tax Mistakes and How to Fix Them
- When to Ask a Tax Professional
- Frequently Asked Questions
- What is the deadline for taking an RMD?
- Do RMDs have to be taken by December 31, and can I request an automatic payment?
- Are RMDs taxed as ordinary income?
- Can I delay an RMD because I am still working?
- What happens if I miss an RMD?
- Do I need an RMD from an inherited IRA?
- Conclusion
What You Need
Gather the paperwork before you start calculating anything. Pull every one of these into one place, because the most common failure is reviewing one account out of four.
- Current statements for every retirement account you own or inherited, not just the one you contribute to. Include the December 31 value on each.
- Beneficiary designations for every account, and the death-benefit paperwork for any account you inherited.
- Your prior-year federal tax return, including the forms that report retirement distributions.
- Current IRS guidance, mainly Publication 590-B, Distribution Rules for Qualified Retirement Plans and IRAs, plus IRS Topic no. 590.
- Your estimated-tax records for the current year and the withholding elections you already have on file with each custodian.
- A contact list for every plan administrator and custodian, with the phone number for the retirement services line rather than the general call center.
- A record of this year’s other income: Social Security, wages, a sale, a pension, a rental property, or an unusually large deductible expense.
The same list works for a traditional IRA, a workplace 401(k) or 403(b), a SEP or SIMPLE IRA, a 457 plan, a TSP, and an account you inherited. The rules differ by account type in ways that matter, which is why step one below starts with an inventory rather than a formula.
If you contribute through an employer, the plan document and the plan administrator matter more than any general guidance. Some plans permit a different calculation method than the IRS worksheet, and that changes the number you are required to take.
Step-by-Step: How to Avoid RMD Tax Surprises
1. Identify Every Account That May Require an RMD
Traditional IRAs, 401(k) and 403(b) plans, SEP and SIMPLE IRAs, most 457 plans, the TSP, and inherited accounts generally all require a distribution at some point. The exemption list is short, and the common ones are a Roth IRA you own yourself, a Roth 401(k) contribution you made, and accounts you have already emptied. Notice that Roth conversion balances sit inside a traditional IRA, so the conversion itself does not create a separate account but it does create taxable income in the year you convert.
Two traps catch people here. The first is the account you forgot: an IRA opened at a previous job, a dormant SEP from a side business years ago, or an inherited account you never claimed. The second is assuming that because the accounts are separate, the minimums are separate. In a traditional IRA, a single calculation can be applied across all of your traditional, SEP and SIMPLE IRAs combined, which is often smaller than adding up each account on its own.
Write the inventory as a simple list: account type, custodian, December 31 value, and whether a spouse is covered by the same plan. If any line is uncertain, ask the plan administrator in writing and keep the reply.
2. Confirm Your Age and Whether an Exception Applies
SECURE Act 2.0 moved the starting age up on a schedule based on birth year. The trigger age is 73 for people born 1960 through 1962, 74 for those born 1963 through 1965, and 75 for those born 1966 and later. Anyone older than those brackets reached the prior age schedule already. Because the age is determined by birth year rather than by the calendar year alone, two people turning 73 in the same year can face different deadlines in later years.
There are two genuine exceptions, and both are narrower than most readers expect. The still-working exception applies to a retirement plan maintained by an employer, and it lets you postpone the distribution while you are still employed, with a few important limits: it does not generally apply to an IRA you set up yourself, the employer plan has to meet plan rules, and taking the distribution postpones it rather than eliminating it. The still-working spouse exception is separate: a spouse who is not a plan participant can defer their own RMD while the working spouse’s plan requires them to take theirs. These exceptions do not reduce the RMD once you are no longer eligible.
Check beneficiaries, plan terms, and any Roth conversion you made in the year. Those three items change the calculation, and none of them appear on a generic checklist online.
3. Calculate the Correct Distribution Amount
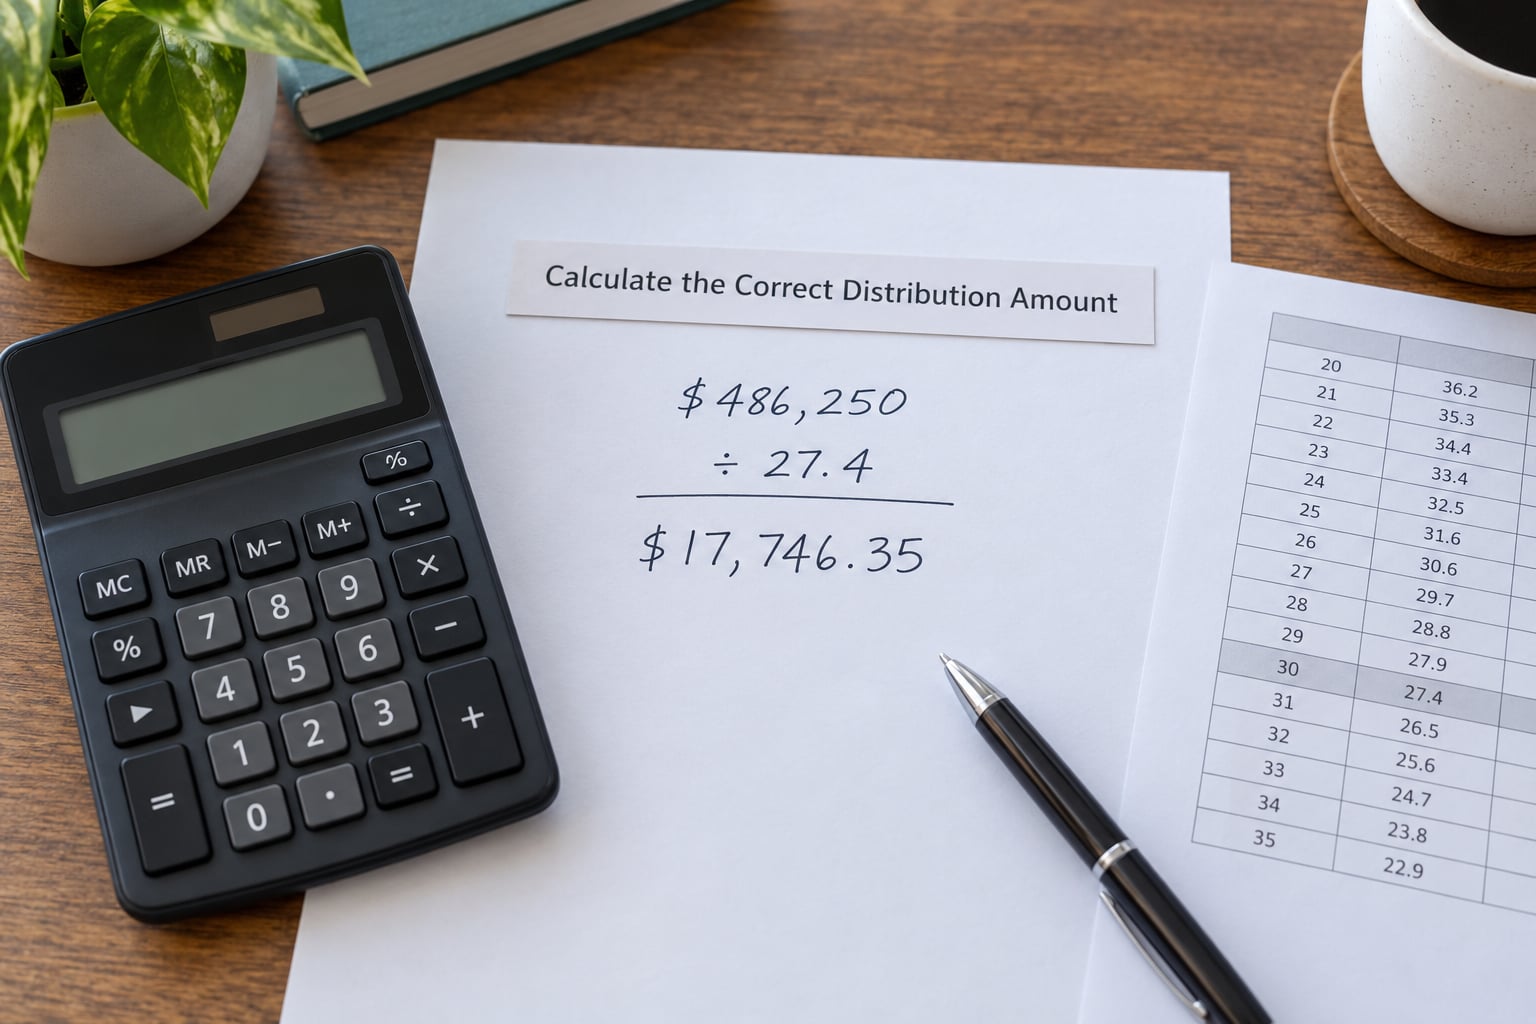
The standard method is simple: take the account value on December 31 of the prior year and divide it by a divisor from the Uniform Lifetime Table in Publication 590-B. The divisor is not a fixed number for life, which surprises people. It is a different figure for each age, and it changes as the table is updated, so pull the current table rather than a saved PDF from a few years back.
For illustration, a traditional IRA with a December 31 balance of 600,000 and an age of 73 uses a divisor of 26.5, giving a required minimum of 600,000 divided by 26.5, or 22,641 approximately. Change the divisor to the one published for the following year and the required amount changes on its own, with no change to the balance. That is why the number on last year’s statement is not a reliable estimate for this year.
Two cautions on the calculation. Employer plans are permitted to use a different method, and some do, so the plan administrator’s figure controls. And an inherited account is not calculated this way at all, because the owner is no longer you; the rules for that account run on a separate schedule and often on a separate timetable.
Record the divisor you used and the source you took it from. When the tax year ends you will want to know whether the amount you withdrew matched the one you computed, or whether a mid-year change in the table moved the target.
4. Review the Deadline and Plan the Payment
For most accounts the distribution must be completed by December 31 of the year your RMD age is reached, though a workplace plan can set an earlier deadline for its own plans. Missing the date triggers the penalty described below, so the operational detail that matters is settlement: transferring funds in late December is not the same as the custodian processing the withdrawal in late December. Bank transfers take days, and some custodians have a cutoff for year-end requests that is well before the last business day.
Ask your custodian for the processing cutoff in writing, and count backward from it rather than from December 31.
Two rules are worth knowing because they are frequently misunderstood. In the first year the requirement begins, the deadline is April 15 of the following year, but the distribution is then treated as belonging to the prior tax year, which means two required amounts in twelve months and two tax bills built from them. That relief is for a missed first year, not a scheduling tool. And the IRS permits a single required amount to be taken in two installments, at roughly half each, six months apart, which is useful in a year when the withdrawal would otherwise create one very large taxable event.
You are also allowed to take more than the minimum, and often should. A required minimum is a floor, not a spending plan. The frame that helps most people is that the distribution is a transfer between your tax-deferred account and your taxable account, with a tax bill attached, and the account you want to fund is the taxable one.
5. Estimate the Tax and Withholding Consequences
The distribution is added to your other income for the year and taxed at ordinary rates, and that single fact creates several knock-on effects. It can push you into a higher bracket on income you would otherwise have kept in a lower one. It can make a portion of Social Security taxable, because the calculation is based on combined income. And it counts toward modified adjusted gross income, which drives the Medicare income-related monthly adjustment amount, usually with a two-year lag between the income year and the premium year. One withdrawal, three separate increases.
The estimate itself is arithmetic rather than magic. Take the RMD, add it to your other gross income, subtract anything that reduces the taxable base, and read the result against the bracket schedule for your filing status. A worked comparison, using round figures:
- Without planning: other income of 40,000 and an RMD of 22,641 give taxable income of about 62,641 before deductions, credits and any charitable giving.
- With a conversion made two years earlier: 20,000 was converted in an earlier year when income was lower, the balance is smaller, the RMD is smaller, and the taxable amount this year is lower by the reduction in the account plus the benefit of tax paid earlier at a lower rate.
That second case is the whole argument for planning early. A conversion ladder spreads income across lower-income years, so the account you draw from in your seventies is a smaller account and the required amount falls with it. This is an illustration of the arithmetic, not a prediction for your situation. Conversions are taxable in the year you make them, and the rate you pay depends on the bracket that lands you in, so the sequence has to be planned rather than assumed.
Build the estimate into a simple worksheet: projected RMD, other income, projected taxable income, estimated federal tax, estimated state tax, and the difference between that tax and what you have already paid through withholding and estimated payments. The gap is the surprise you are trying to prevent.
Be clear about what this worksheet is. It is a planning estimate that uses the current year’s projected numbers, and it is not a tax return. Taxes, rates, and thresholds change, and a professional should confirm any position you intend to rely on.
6. Check for Taxes That Are Not Automatically Withheld
Many distributions arrive with no tax withheld at all, and that is the single most common cause of the April bill retirees did not see coming. Federal withholding on a retirement distribution is optional, not automatic, and many custodians default to zero. Your plan may also withhold for federal but not for your state, and a handful of states have no income tax on retirement distributions at all, so the state question is specific to where you live and to where you were living on the date of distribution.
You have a stronger option than guessing. Custodians can withhold a larger percentage of the distribution, in some cases up to the entire amount, for federal and state tax. The IRS treats tax withheld on a retirement plan distribution as paid evenly across the year, which has a real effect: the amount is treated as already-paid tax spread across the quarters, so a large Q4 payment no longer lands as one lump. Retirees on forums report running their entire annual withholding out of the distribution this way, at rates they calculate from their own return, and describe never receiving a separate bill as a result. It is a widely used approach, and the mechanics are yours to set.
The practical sequence: contact the custodian, ask what percentage is currently being withheld and whether it can be changed, set the rate you want for the next distribution, and then confirm the change appears on the distribution confirmation. Keep the confirmation with your year-end records. If you take a series of smaller distributions instead of one, the withholding election is made separately for each one, so it is easy to set it on the first and forget the rest.
7. Keep Records and Reconcile the Distribution
File the confirmations the day they arrive rather than at filing time. For each account you want the distribution date, the gross amount, the net amount actually delivered, the amount withheld, and the custodian’s confirmation number. Add the corrected year-end statement for every account you touched, and the plan’s confirmation of the amount it calculated.
At tax time, match those records against the tax forms. Form 1099-R reports the gross distribution and the taxable portion, and the distribution code in box 7 tells you how the IRS classified it. Form 5498 arrives when tax was withheld on a distribution. The numbers on those forms should tie to what your custodians sent you, and a mismatch is a filing error waiting to happen.
If something looks wrong, contact the custodian before you file rather than after. The usual causes are a mismatched owner or beneficiary record, a wrong distribution code, a distribution reported to the wrong Social Security number, or a partial distribution reported as a full one. Custodians can correct a reporting error. They cannot fix it after the statute of limitations closes, and correcting it before you file is far easier than amending a return. Keep copies of every correction letter.
Common RMD Tax Mistakes and How to Fix Them
Each of these has a straightforward correction, and several of them are the reason a careful reader still gets a bill they did not expect.
Waiting for the last week of December. The withdrawal is not complete until the custodian has processed it, and bank transfers do not settle instantly. Fix it by asking for the processing cutoff in writing and setting your own internal deadline three weeks earlier.
Using the April 15 first-year relief as a routine deadline. The delay treats the distribution as belonging to the prior year, so you get two required amounts and two tax bills within twelve months. Fix it by taking the first distribution in its own calendar year unless a genuine emergency makes that impossible.
Forgetting an account. An old IRA, a dormant SEP from a business you closed, or an inherited account you never claimed is the most common cause of an understated distribution. Fix it by rebuilding the inventory annually rather than reusing last year’s list.
Treating the RMD as spendable income. The money does not disappear, and someone who spends it and then faces a large tax bill has funded the bill with after-tax dollars. Fix it by sending the distribution directly into a taxable brokerage or savings account and treating it as a transfer, not income to budget from.
Assuming a charitable distribution reduces the RMD. A qualified charitable distribution is a gift directly from the retirement account, and it satisfies the required amount without adding taxable income. A regular charitable deduction does not: you take the full RMD, then deduct the gift. The distinction decides which one you want.
Calculating from the wrong number. Using last year’s divisor, a current-year balance, or a table saved years ago produces an amount that looks reasonable and is wrong. Fix it by recording the divisor and its source with the calculation itself.
Selling appreciated shares to fund the withdrawal in a down year. A distribution can be satisfied in kind, meaning shares move from the retirement account to a taxable account and nothing is sold inside the IRA. That avoids realizing a loss at the worst point in a declining market. Fix it by asking the custodian about in-kind distributions to a linked brokerage account before the market drop, not during it.
Assuming federal withholding covers state tax. Federal and state withholding are separate elections, and a distribution with a large federal hold can still leave a state bill. Fix it by setting both elections and by checking whether your state taxes retirement distributions at all.
Filing without reconciling. Reading a 1099-R once and moving on means a wrong distribution code or a mismatched owner record goes unnoticed. Fix it by matching every form to the custodian confirmations, and by resolving discrepancies in the spring rather than after filing.
When to Ask a Tax Professional
Some situations are genuinely beyond a checklist, and a professional review is worth the cost well before a deadline. Inherited accounts are the clearest case, because the distribution rules for a beneficiary IRA run on a different schedule, an eligible rollover decision must be made within a defined window, and spousal continuation has its own requirements that a self-directed approach tends to get wrong.
Multiple employer plans raise a separate set of questions, particularly around how two plans treat you and whether a second plan’s distribution can offset the first. Situations involving trusts, estate planning, or a large charitable program need a professional because the answer depends on documents you will not have in front of you. So does Roth conversion sequencing when the goal is to move income into lower years without landing above a bracket threshold or a Medicare premium threshold.
State questions deserve the same treatment, especially a move across state lines in the year of the distribution, since some states look at where you lived on the date of the distribution. And if the custodian’s reporting and your own records disagree, get a second opinion before you amend anything.
Rules and rates change. Legislation has moved RMD ages, penalty levels, and catch-up provisions more than once, and the figures in this article reflect the framework in place as of 2026. A CPA or tax adviser should confirm the final position for your situation, and the IRS primary sources are the right place to start when an answer conflicts with what you read anywhere else.
Frequently Asked Questions
What is the deadline for taking an RMD?
For most accounts, the required minimum distribution must be completed by December 31 of the year you reach your RMD age, which is 73 for people born 1960-1962, 74 for those born 1963-1965, and 75 for those born 1966 and later. In the first year the requirement applies, the deadline is April 15 of the following year, but the distribution is then treated as belonging to the prior tax year, so you end up with two required amounts in twelve months. Employer plans can set an earlier deadline, and the custodian’s processing cutoff usually comes before the calendar date.
Do RMDs have to be taken by December 31, and can I request an automatic payment?
The distribution has to be completed by the deadline, but it does not have to be one lump. The IRS permits a single required amount to be taken in two roughly equal installments, six months apart, which spreads the taxable income across two years. Many custodians also offer an automatic distribution setting, where the required amount is withdrawn on a fixed date each year. Ask the plan administrator whether automatic distributions are permitted, since an employer plan controls its own rules, and confirm the setting well before the year begins rather than in December.
Are RMDs taxed as ordinary income?
Yes. A required minimum distribution from a traditional IRA, 401(k), 403(b), SEP or SIMPLE IRA is added to your other income for the year and taxed at ordinary income tax rates, not capital gains rates. That is why a large distribution can push income earned elsewhere into a higher bracket. It also counts toward modified adjusted gross income, which can make a portion of Social Security taxable and can trigger a Medicare income-related premium adjustment two years later. Roth IRAs you own yourself do not require a distribution at all.
Can I delay an RMD because I am still working?
Sometimes, and the exception is narrower than most people expect. The still-working exception applies to a retirement plan maintained by an employer, letting you postpone the distribution while you remain employed, subject to plan rules and some limits on IRA rollovers into the plan. It generally does not apply to an IRA you established yourself. A separate still-working spouse exception can defer the non-working spouse’s RMD in some cases. Either way, the delay postpones the distribution, it does not reduce it, and it ends once you stop working.
What happens if I miss an RMD?
The shortfall is generally subject to a 50 percent excise tax. If you take the missing amount by the end of the second calendar year after the year it was due, the rate is reduced to 25 percent. The penalty can be waived if the shortfall is small and you were not otherwise liable to pay tax on the distribution, though the size of that waiver is limited. Correcting promptly is far cheaper than the headline rate, and requesting automatic distributions for future years prevents the problem from recurring.
Do I need an RMD from an inherited IRA?
The rules differ from an IRA you own, because the original owner is no longer the account holder. A beneficiary IRA of a deceased person who was past the required age generally has to be distributed within a short window, while one that qualifies as a designated Roth IRA or an eligible rollover can be spread over a longer period. Deciding correctly depends on the original owner’s age at death and the account’s classification, and the choice window is limited. This is one area where a professional review is usually worth arranging before you touch the account.
Conclusion
If you do one thing this quarter, build the account inventory. List every retirement account you own or inherited, the December 31 value in each, and the plan contact for each one. That list tells you whether a distribution applies at all, and it takes less than an hour.
Then check your birth year against the current schedule, calculate the amount using the divisor published for this year rather than last year’s, and find out your custodian’s processing cutoff well before December. If the tax on that distribution is going to be larger than you expect, the levers are a Roth conversion made in an earlier year, a qualified charitable distribution, an in-kind transfer instead of selling shares, and setting withholding to cover the bill as you go. Reviewers on retirement forums consistently report that the withdrawal itself is never the problem, and that knowing the number in advance is what turns an RMD into a plan rather than a surprise.
Confirm the current rules against IRS Publication 590-B and IRS Topic no. 590 before you act, since ages, penalty levels, and thresholds have all moved with recent legislation. Inherited accounts, multiple workplace plans, trusts, and any Roth conversion plan are worth a conversation with a CPA or tax adviser, because a wrong assumption there is expensive to unwind.