Knowing how to talk to your partner about money works best when you start with feelings and values before you ever open a spreadsheet, then follow a scheduled plan rather than waiting for a fight. Most couples who get this right pick one specific issue, share the actual numbers, listen without interrupting, and leave the conversation with agreed next steps and a date to check in.
That sounds simple. It isn’t, because money carries history. What your parents said about money, what you watched go unpaid, or the first time a bill surprised you tends to follow you into every argument with the person you love. Those older lessons explain most of the heat.
The good news is that this is a practice, not a personality trait. Couples who talk about money regularly report less financial stress and fewer surprises, because the decisions happen on purpose instead of by drift.
What follows is a seven-step plan you can run in a single evening, plus the mistakes that derail the conversation most often.
Table of Contents
- What You Need
- Step-by-Step: How to Talk to Your Partner About Money
- Step 1: Decide What You Need to Discuss
- Step 2: Gather the Important Numbers
- Step 3: Choose a Calm Time and Place
- Step 4: Use Neutral, Specific Language
- Step 5: Listen and Ask Questions
- Step 6: Agree on Financial Goals and Rules
- Step 7: Set a Follow-Up and Check-In
- Common Mistakes
- Frequently Asked Questions
- How do I start a money conversation with my partner?
- What if my partner refuses to discuss money?
- How should couples discuss debt and unpaid bills?
- How do we handle different incomes or spending habits?
- Should couples combine all their finances?
- How often should we review our household budget?
- Conclusion: Start With One Shared Financial Decision
What You Need
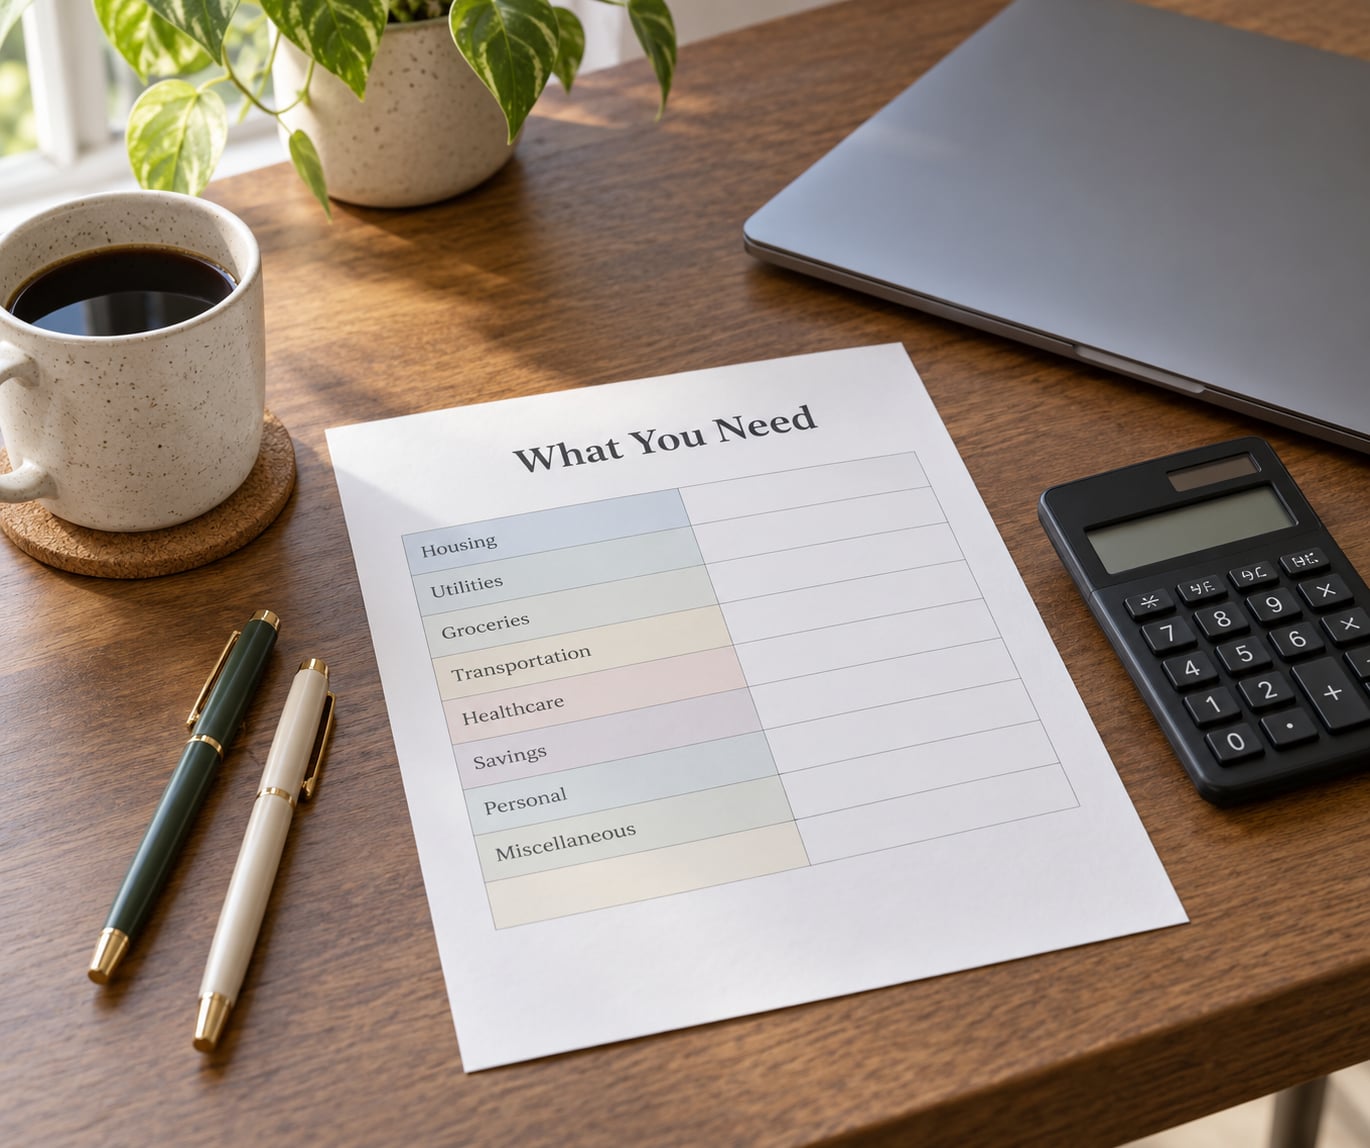
You need far less than people assume. You need accurate information and a clear purpose, not a perfect budget and not a fight.
Gather the real numbers first: each person’s take-home income, fixed monthly bills with due dates, total debt balances and interest rates, current savings, and any large expense coming in the next six months. Estimates create arguments that facts end. If one of you has been avoiding their statements, opening them at home is the single highest-value thing you can do before the conversation.
Second, agree on what the conversation is for. Write one sentence on paper: “We are going to agree how to cover the car payment and build up our emergency savings.” A single sentence keeps a talk from turning into a full audit of every purchase from the last three years.
Third, pick a time when neither of you is tired, hungry, or already upset. Saturday morning over coffee works better than nine at night after a long day. Give yourself sixty to ninety minutes.
Fourth, decide what you are willing to say yourself. Disclosure only works when it goes both ways. If you are bringing up a debt or a habit, plan to name your own numbers in the same breath.
Step-by-Step: How to Talk to Your Partner About Money
Step 1: Decide What You Need to Discuss
Pick one or two issues, never the whole relationship. A new car, a credit card balance, a shared emergency fund, or a lease renewal all work as a single agenda item.
Couples who try to settle income, spending, debt, investments, and the future in one sitting tend to quit halfway through. What matters is that you return with a second session rather than declaring the relationship broken over a phone bill.
Step 2: Gather the Important Numbers
Pull the same set of figures on both sides. Incomes net of deductions, fixed costs, revolving balances, and savings balances should all be written down before you sit down together.
A shared spreadsheet works fine, and so does a budgeting app if you both already use one. The format matters less than both people looking at the same numbers at the same time. Someone keeping a private mental tally while the other shares a screen is not a joint budget.
Step 3: Choose a Calm Time and Place
Never open this subject during a fight, on the way to an event, or at bedtime when the goal is sleep. Pick a private room with no interruptions and no phones face up.
Going out for a meal works because the setting signals this is not a confrontation, though the car is an equally common choice. At home, a kitchen table after the kids are down works. Whatever you pick, put it on the calendar like a dentist appointment so it stops feeling like an ambush.
Step 4: Use Neutral, Specific Language
Describe what you observed and what you want, not who the other person is. Compare “you never think about money” with “the subscription charges have added up to a few hundred a month and I want us to look at which ones we actually use.”
I-statements carry this well. Say “I feel anxious when our savings are this low” instead of “you’re reckless.” Then make a specific request: “Can we look at the last three months of spending tonight?”
Phrases to drop from the conversation entirely: irresponsible, careless, wasteful, childish, and you always. They invite defense rather than reflection.
Step 5: Listen and Ask Questions
To talk to your partner about money well, you have to actually hear them. Ask open questions and let silence sit for a few seconds. “What’s worrying you about our finances?” gets you more than “why do you spend so much?”
Reflect back what you heard before you respond. “So the worry is that we have nothing set aside if the car goes down. That tracks with how I’ve been feeling.” That sentence alone defuses half of what would have become an argument.
Then sort what you found. A misunderstanding about a bill is a fix-it problem. A genuine difference in values, like one of you saving for a down payment and the other preferring travel now, is a trade-off you decide together. Neither is a character flaw.
Step 6: Agree on Financial Goals and Rules
End the meeting with decisions written down. Shared financial goals work when they are specific and dated: one month of expenses in an emergency fund by spring, a fixed amount toward the card balance each month, and a number below which either of us checks with the other first.
Agree on which decisions need both signatures. Rent above a certain amount, any new borrowing, and any move that costs more than a deposit should be joint calls. Smaller choices stay individual.
Decide the account structure too. Separate accounts with a shared account for common costs suits couples with different incomes or strong autonomy needs. A single joint account suits couples who want full visibility. The best fit is the one both people can use without resentment, not the one that looks most committed.
Step 7: Set a Follow-Up and Check-In
Leave with two or three assigned actions, an owner for each, and a date. Thirty minutes a month on a fixed day is enough for most couples, plus a longer session whenever something big changes.
Money shifts constantly. A bonus, a layoff, a move, a new child, a parent who gets sick. Put those on the calendar as review points rather than waiting for a crisis to force the conversation. A ten-minute check-in after each one keeps the big annual plan from going stale.
Finally, review what worked. If the conversation turned into three accusations, the problem is usually the agenda or the timing, not the two of you.
Common Mistakes
Almost every money fight I see follows the same handful of patterns, and each has a straightforward fix.
The ambush. Bringing up a surprise bill at the end of a long day guarantees a defensive response. Fix: name the time when you want to talk and let the other person say yes, or suggest two options and let them pick.
Scorekeeping. Remembering every purchase from three years ago turns a conversation into a trial, and the other person stops sharing to protect themselves. Fix: agree that past spending is not evidence. Talk about the next six months, not the last six years.
Debating every purchase. Asking permission to buy a fifteen-dollar item will eventually exhaust both of you. Fix: set a small threshold below which each person decides alone, and reserve discussion for bigger commitments.
Mixing household and personal money. One budget trying to control groceries, savings, hobbies, and a shared car payment ends up with everyone resenting something. Fix: agree on a personal amount each of you keeps without explaining, and budget the household separately.
Refusing to revisit the plan. A budget agreed once and never checked becomes fiction within three months. Fix: put the review on the calendar at the time you agree, not later.
Disclosing badly. Hiding a debt until it surfaces destroys more trust than the debt itself. Fix: bring it up before you are asked, state the amount and the interest rate, and propose a payment plan you can actually keep. Revealing something small early builds the trust you will need for the next small thing.
There is also a line worth naming. Different spending styles are normal. Being unable to see your partner’s spending, being given a spending allowance, or having your money tracked without your input is a different thing, and it is worth talking about directly. Shared finances built on pressure do not stay shared.
Frequently Asked Questions
How do I start a money conversation with my partner?
Open with a neutral announcement rather than a complaint: I want us to look at our finances on Saturday morning and I want to hear your view first. Pick one topic, not your whole history, and share one number of your own before asking for theirs. Starting small and going first makes it much easier for the other person to join you.
What if my partner refuses to discuss money?
Name the pattern calmly and set a boundary: I will keep raising this because our decisions get made without me. Then offer three options: a scheduled thirty-minute session, a shared spreadsheet they fill in themselves, or a joint appointment with a financial counselor. If refusal continues and money decisions still affect you, that is a boundary you get to set, not a topic to argue about forever.
How should couples discuss debt and unpaid bills?
Bring it up before it is discovered, state the balance, interest rate, and minimum payment, and propose a repayment plan in writing. Agree on a monthly amount each of you can keep without rent or groceries falling short, and put extra payments toward the highest interest rate first. Review the payoff date at each monthly check-in rather than every week.
How do we handle different incomes or spending habits?
Different incomes are common and rarely the real problem; resentment about contribution is. Use a shared account for common costs funded by a percentage of each income, and give each person a personal amount they decide alone. For habits, agree on a spending amount with no explanation needed, and talk about what the money is for rather than how much it was.
Should couples combine all their finances?
Not always. A single joint account gives full visibility and simplifies shared costs, which suits couples who prefer full transparency. Separate accounts with a joint account for common costs preserves independence and works well with unequal incomes or strong personal spending habits. Many couples use the hybrid setup and revisit it as their situation changes.
How often should we review our household budget?
Thirty minutes a month is enough for most couples, on the same day each month, plus a longer review when income, expenses, or goals change. A short standing check-in keeps the budget honest and stops a missed month from turning into a fight. Quarterly is the realistic floor if monthly feels like too much, but skipping it entirely is what lets small problems compound.
Conclusion: Start With One Shared Financial Decision
Knowing how to talk to your partner about money does not require fixing your whole financial life in one evening. Pick one small, specific issue this week, share the real numbers for that issue, listen long enough to understand their view, and agree on both a next step and a date to check in.
Then do it again next month. The couples who get calm about money are not the ones who earned more. They are the ones who made the conversation ordinary.
This is general education, not individual financial advice. Tax, debt, and account rules differ by state and change over time, so check the specifics with a qualified financial professional.